

Blogs
PW Consulting: Worldwide Cold Ramming Paste Market Hits $487.04M in 2025, Projected 4.0% CAGR to 2032
By PW Consulting, 2026-09-17
Strategic Intelligence for the Next Cycle: Why the Worldwide Cold Ramming Paste Market Demands Precision in 2026
The global Cold Ramming Paste (CRP) market stands at a critical inflection point. As industrial operators navigate tightening environmental regulations, raw material volatility, and intensifying competition for process efficiency, the ability to anticipate market shifts is no longer optional—it is a strategic imperative. Our latest Worldwide Cold Ramming Paste Market research delivers a comprehensive, data-driven roadmap for enterprise decision-makers operating across aluminum smelting, ferroalloy production, silicon manufacturing, and heavy metallurgical furnace applications. This article outlines the structural dynamics, competitive realities, and forward-looking intelligence embedded in the report, demonstrating why precise market intelligence will define competitive advantage throughout the 2026–2032 forecast horizon.
Worldwide Cold Ramming Paste (CRP) Market
Macro Market Trajectory: From Recovery to Sustained Expansion
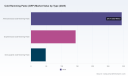
The CRP market has demonstrated remarkable resilience through a period of structural adjustment. Historical tracking from 2020 through 2025 reveals a market that expanded from approximately 385.4 million USD to 487.04 million USD, reflecting both demand recovery and supply-side modernization. The current baseline anchors at 487.04 million USD, with near-term projections indicating a measured climb to 495.06 million USD in 2026. Looking further ahead, the market is positioned to reach 640.9 million USD by 2032, translating to a compound annual growth rate of approximately 4.0 percent across the full forecast window.
These figures do more than chart volume—they signal a maturing ecosystem. The gradual upward trajectory reflects steady electrification of smelting operations, ongoing furnace maintenance cycles, and the gradual replacement of legacy sealing materials with engineered carbon-based formulations. Yet the true strategic value lies beneath the headline numbers. The forecast period exposes inflection zones where capacity shifts, regional rebalancing, and product substitution will alter procurement economics. Companies that treat CRP as a commoditized input risk margin erosion; those that align sourcing, formulation strategy, and supplier partnerships with forward-looking market intelligence will capture disproportionate operational stability.
Segmentation Dynamics: Type, Application, and Regional Realities
The market architecture is defined by distinct segmentation layers that collectively shape pricing behavior, supply chain design, and technology adoption. By product type, the landscape is anchored by anthracite-based formulations, complemented by graphite-based and semi-graphitic variants. Each category carries unique performance profiles, thermal stability boundaries, and cost structures that determine suitability across different furnace environments. By application, aluminum smelting cells dominate consumption, while blast furnaces and submerged arc furnaces represent specialized but strategically vital demand nodes. Regional distribution further complicates the picture, with Asia Pacific commanding the largest share of market activity, followed by Europe, the Middle East and Africa, North America, and Latin America.
Our analysis deliberately avoids superficial percentage breakdowns. Instead, the report maps how these segments interact under real-world operating conditions. Procurement teams must understand not just which segment is largest, but which segments exhibit the highest sensitivity to binder substitution, which applications face the most acute downtime risks during paste replacement cycles, and where regional supply constraints could trigger price dislocation. The interplay between type, application, and geography creates a multi-dimensional decision matrix that generic market summaries consistently fail to address.
Competitive Landscape: Consolidation, Specialization, and the Battlefield for Performance
The CRP market is neither fully fragmented nor monolithically concentrated. With a CR3 of 45.5 percent and a CR5 of 62.3 percent, the industry exhibits moderate-to-high concentration, yet significant room remains for specialized players to compete on formulation excellence, regional service coverage, and sustainability credentials. Our report profiles the core companies shaping this competitive arena, translating corporate positioning into actionable supplier evaluation criteria.
- Elkem ASA anchors its offering around ELSEAL cathode ramming paste variants designed to seal voids between prebaked cathode blocks and prevent electrolyte leakage in aluminum electrolysis cells. Its operational footprint extends to Brazil, reinforcing a global supply posture that balances technical consistency with regional availability.
- Maruti Electro Carbon leverages advanced manufacturing technology to deliver formulations with strong thermal stability and resistance in high-temperature environments, primarily serving aluminum and adjacent industrial sectors.
- Henan Rongxing Carbon Products Co., Ltd. has built a multi-decade portfolio across carbon metallurgical products, now including eco-friendly cold ramming paste variants for electrolytic cells and furnace lining applications.
- Bawtry Carbon Ltd focuses on aluminum smelting applications, emphasizing cathode and sidewall use cases through dedicated ramming paste series engineered for consistent sealing performance.
- Ningxia Hongyuan Huida Industrial Co., Ltd. produces environmentally conscious cold ramming paste series for cathode sealing and industrial furnace use, capitalizing on proximity to anthracite supply bases and a broader electrode paste ecosystem.
- Luoyang Longxin Furnace Co., Ltd. integrates cold ramming paste with carbon electrode paste and sealed electrode paste, serving metallurgical furnace operators that value integrated product compatibility.
- Shandong Robert New Material Co., Ltd. emphasizes thermal stability, density, and adhesion in its formulations, targeting aluminum electrolysis cells and blast furnace environments where performance consistency is non-negotiable.
- Wuhai Cowin Carbon Co., Ltd. positions cold ramming paste within a broader carbon and graphite product range, addressing ferroalloy, silicon, and calcium carbide industries that demand durable furnace lining materials.
- Ningxia Coalician Carbon & Coke Co., Ltd. supplies environmentally oriented furnace lining materials for silicon, ferroalloy, and calcium carbide electric furnaces, promoting graphitized, gap-free properties that support both new installations and repair linings.
- Carbone Savoie has advanced a fully eco-friendly cold ramming paste portfolio designed to reduce or eliminate PAH content, with formulations tested at industrial sites to validate performance under real smelting conditions.
The strategic implications are clear. Large, integrated suppliers compete on scale, global logistics, and certified consistency. Regional specialists compete on technical responsiveness, localized service, and formulation adaptation. Meanwhile, sustainability-driven entrants are reshaping procurement preferences by offering low-PAH or zero-PAH alternatives that align with corporate environmental mandates. Evaluating supplier risk, negotiating long-term agreements, and designing dual-sourcing strategies all require granular insight into how these players position themselves across type, application, and geography.
Market Forces Reshaping Procurement and Formulation Strategy
Several structural forces are redefining how operators source, specify, and manage cold ramming paste. First, raw material composition remains foundational. CRP is typically formulated using calcined anthracite, artificial graphite, and coal tar pitch or alternative binders. The precise balance of these feedstocks determines electrical resistivity, thermal stability, adhesion, and service life. Recent technical literature indicates that finished applications often target electrical resistivity below 65 Ω·mm²/m, with binder content typically spanning 55–70 percent asphalt or coal tar pitch alongside anthracene oil and functional additives. Procurement teams that understand these formulation levers can better assess supplier claims, anticipate price sensitivity to feedstock movements, and select products aligned with specific furnace operating parameters.
Second, environmental and occupational health regulations are accelerating formulation transformation. Conventional coal tar pitch binders can release polycyclic aromatic hydrocarbons during use, prompting the development of eco-friendly alternatives utilizing furan resin, lignin, or treated pitch with zero or reduced PAH content. Industry studies and manufacturer technical documentation have increasingly highlighted these shifts, while major smelting operators have begun implementing environment-friendly cold ramming mixtures designed to limit the liberation of hazardous volatile organic compounds such as benzo pyrene. The regulatory trajectory favors suppliers that can demonstrate measurable environmental performance without compromising sealing integrity, thermal stability, or installation practicality.
Third, application-specific performance requirements are becoming more rigorous. Aluminum smelting cells demand materials that withstand electrochemical environments, thermal cycling, and mechanical stress during maintenance windows. Blast furnaces and submerged arc furnaces impose distinct constraints related to high-temperature stability, lining adhesion, and compatibility with repair cycles. The market is therefore moving away from one-size-fits-all procurement toward specification-led sourcing, where paste selection is tied to cell design, operating temperature profiles, downtime tolerance, and environmental compliance targets.
What Our Report Delivers for 2026 Decision-Making
The Worldwide Cold Ramming Paste Market research is structured to convert complex market signals into executable strategy. The report moves beyond descriptive statistics to provide a practical intelligence toolkit for executives, procurement leaders, technical managers, and investors. Key deliverables include:
- A full historical reconstruction from 2020 through 2025, establishing baseline behavior, recovery patterns, and volatility triggers that inform baseline scenario planning for 2026 and beyond.
- A forward forecast extending through 2032, with annual revenue projections that enable capacity planning, budget modeling, and investment timing decisions across the forecast horizon.
- Segment-level analysis that clarifies how type, application, and regional demand interact, helping organizations identify the most resilient procurement categories and the segments most exposed to substitution or regulatory shifts.
- A competitive benchmarking framework that evaluates core suppliers on operational footprint, formulation emphasis, sustainability positioning, and service model, supporting vendor selection, negotiation strategy, and supply chain diversification.
- A market dynamics assessment that integrates raw material feedstock considerations, binder substitution trends, environmental compliance pressure, and application-specific performance requirements into a cohesive view of risk and opportunity.
- Strategic scenario mapping that highlights where capacity evolution, regional rebalancing, and product innovation are likely to alter pricing logic, availability, and total cost of ownership for end users.
Importantly, the report is designed to support decisions that must hold up under operational scrutiny. Procurement teams can use the intelligence to align contract structures with anticipated market movement. Technical leaders can map formulation characteristics to furnace performance requirements. Strategy and finance groups can stress-test capital allocation against realistic demand pathways. The objective is not to provide a static snapshot, but to equip organizations with a living framework for evaluating supplier options, anticipating regulatory impact, and positioning procurement strategy ahead of market inflection points.
Why This Intelligence Matters Now
The 2026 operating environment will reward precision. As environmental standards continue to tighten and furnace operators seek to reduce downtime, extend lining life, and maintain process stability, the selection of cold ramming paste becomes a strategic lever rather than a routine consumable purchase. Suppliers that invest in eco-friendly formulations, consistent thermal performance, and application-specific engineering are gaining prominence in procurement evaluations. At the same time, regional demand patterns, feedstock availability, and competitive concentration are creating new considerations for sourcing resilience.
Electrode Paste Market
Our research isolates these dynamics into a structured, decision-ready format. It enables organizations to move beyond intuition and generic market narratives, grounding their strategy in validated sizing, credible segmentation logic, and a realistic assessment of the competitive field. Whether the goal is to optimize supplier portfolios, evaluate entry opportunities, benchmark against industry peers, or prepare for regulatory-driven formulation shifts, the report provides the analytical foundation required to act with confidence.
Accessing the Full Strategic Picture
The macroeconomic trajectory, segmentation architecture, competitive profiles, and regulatory influences discussed here represent only the surface of what the report contains. Detailed segment sizing, regional demand structures, application-specific consumption patterns, supplier positioning matrices, and forward scenario analysis are all developed to support precise, evidence-based decision-making. For organizations that require complete visibility into how the worldwide cold ramming paste market will evolve through 2032, the full research publication offers the depth necessary to convert market intelligence into operational advantage.
The strategic window for aligning procurement, technical specification, and supplier strategy is open now. Enterprises that invest in comprehensive market intelligence today will be better positioned to manage cost structures, mitigate supply risk, and respond to the formulation and compliance shifts that will define the next phase of market growth.
For detailed analysis of this topic, please visit the official page: Worldwide Cold Ramming Paste (CRP) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Radiator Flushing Chemicals Market Hits $225.5M in 2025, 5.48% CAGR to 2032
By PW Consulting, 2026-09-17
Global Radiator Flushing Chemicals Market 2026: Executive Intelligence Brief
Market Trajectory and Strategic Relevance
The Worldwide Radiator Flushing Chemicals Market has entered a decisive inflection period. Between 2020 and 2025, global revenue expanded from 172.4 million USD to 225.5 million USD, reflecting a compound trajectory that has accelerated through fleet modernization, extended cooling-system intervals, and heightened aftermarket maintenance awareness. Our latest research traces this momentum through a detailed 2026-2032 forecast window, during which the market is projected to reach 327.61 million USD, underpinned by a forecasted CAGR of 5.48 percent. This growth trajectory is not merely a function of volume expansion; it signals structural shifts in formulation strategy, regional sourcing dynamics, and competitive positioning that demand proactive planning from chemical manufacturers, distributors, and automotive aftermarket operators.
For executives calibrating 2026 budgets, capacity investments, and go-to-market strategies, the market presents a nuanced opportunity landscape. Demand is increasingly shaped by the interplay of raw material price cycles, evolving engine architectures, and regional maintenance habits. Understanding where margin pools are forming, which vehicle segments are outpacing baseline growth, and how leading manufacturers are adapting their product architectures requires more than top-line figures. It requires a granular view of competitive positioning, formulation differentiation, and regional demand intensity that our research delivers in a structured, decision-ready format.
Formulation Architecture and Segment Leadership
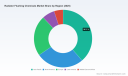
The product chemistry landscape remains anchored in acid-based and alkaline-based formulations, with solvent-based variants capturing a distinct niche tied to specialized cleaning performance and equipment compatibility requirements. Acid-based chemistries continue to lead in total revenue contribution, driven by their established efficacy in removing mineral scale, corrosion deposits, and coolant degradation byproducts across diverse cooling-system architectures. Alkaline-based solutions maintain strong positioning where compatibility with aluminum components, extended service intervals, and reduced metal erosion are strategic priorities. Solvent-based formulations, while representing a smaller share of total market revenue, are gaining attention in applications where rapid deposit removal, low-foam performance, and targeted system revitalization are critical to service throughput.
Vehicle-type segmentation reveals a hierarchy of demand intensity that reflects broader automotive fleet structures and maintenance behavior. Passenger cars account for the largest revenue pool, supported by high vehicle density, routine cooling-system maintenance cycles, and strong aftermarket retail distribution. Light commercial vehicles form the second major demand pillar, with fleet operators increasingly standardizing preventive cooling-system flushing as part of scheduled maintenance programs. Heavy commercial vehicles represent a specialized segment where extended thermal loads, severe operating conditions, and long service life create differentiated product requirements around deposit control, corrosion suppression, and formulation durability under continuous-duty environments.
Worldwide Radiator Flushing Chemicals Market
Regional demand patterns reinforce the importance of localized distribution strength and product adaptation. Asia Pacific demonstrates the highest revenue concentration, reflecting dense vehicle parc growth, expanding aftermarket networks, and increasing adoption of cooling-system maintenance protocols across both passenger and commercial fleets. North America and Europe maintain robust demand bases shaped by mature service infrastructure, stringent performance expectations, and established brand loyalty in the chemicals and aftermarket segments. Latin America and the Middle East and Africa region contribute targeted growth opportunities where infrastructure expansion, fleet renewal, and increasing awareness of cooling-system care are creating incremental demand. Detailed regional revenue breakdowns, growth differentials, and priority submarkets are mapped comprehensively within the full report to support country-level planning and channel strategy.
Competitive Positioning and Strategic Differentiation
The competitive landscape in radiator flushing chemicals is characterized by a balanced concentration profile, with the top three players collectively commanding approximately 38.45 percent of market revenue and the top five firms accounting for roughly 52.12 percent. This structure indicates both established brand presence and meaningful room for differentiation through formulation innovation, distribution expansion, and service-channel integration. Strategic positioning among the market's core participants reflects a mix of specialty formulation expertise, broad aftermarket reach, and targeted product architectures designed to address specific cooling-system failure modes and maintenance workflows.
Major participants such as Prestone Products Corporation emphasize multistep cleaning functionality, offering cooling-system formulations designed to remove build-up, corrosion, and rust while maintaining compatibility across manufacturer-specific radiator and cooling-system materials. Valvoline Inc. continues to leverage its broader coolant ecosystem, aligning radiator flush products with coolant service lines and promoting contaminant removal as part of integrated cooling-system maintenance. Liqui Moly GmbH focuses on restoring cooling-system performance through formulations intended to eliminate scale, grease, sludge, and deposits across water-cooled engine applications. CRC Industries, Inc. has built recognition around acid-free rapid-flush and rust-removal solutions that target rust, scum, oil, and scale while aiming to revitalize cooling efficiency without aggressive chemical profiles.
Other notable competitive players reinforce the breadth of formulation strategies in the market. Bar's Leaks markets cooling-system cleaners that employ buffing-agent approaches to remove corrosion, sludge, and scale from radiators and cooling systems. BG Products, Inc. produces universal cooling-system cleaners designed to remove scale, oil, mineral deposits, rust, and residues from gasoline and diesel engine cooling systems without requiring neutralization steps. Jelmar LLC, through its CLR PRO line, offers a phosphate-free, ammonia-free, biodegradable formula utilizing lactic and gluconic acids for heavy-scale and rust removal within shorter service windows. Chemtex Speciality Limited supplies non-foaming inorganic blend formulations intended for use during system operation, targeting contaminated coolant, debris, rust, scale, and oily deposits. RX Marine International manufactures both acidic descaler-type and non-acidic cleaner options aimed at removing dirt, grease, scale, grime, solder, and broader contaminants from engine cooling systems. Callington's ROX Pro Radiator Flush concentrates are positioned for targeted removal of oil, grease, and contaminants across vehicle cooling systems.
The competitive narrative is increasingly defined not only by product performance but by how effectively companies integrate formulation advantages with distribution reach, service-channel training, and compliance-aware packaging. Detailed company profiles, product positioning matrices, and competitive benchmarking are provided within the full research to support benchmarking exercises, partnership evaluations, and market-entry planning.
Supply-Side Dynamics and Formulation Cost Exposure
Formulation economics in radiator flushing chemicals are closely tied to feedstock availability, commodity price trajectories, and regional input-cost differentials. Ethylene glycol, a primary upstream feedstock for many coolant-related formulations, experienced strong price behavior early in 2025, followed by weakening conditions and a rebound from year-end lows. For 2026, market indicators point to initial weakness and then range-bound stability in the vicinity of 4,000 to 4,400 RMB per ton amid ample supply conditions. This trajectory matters for manufacturers because cooling-system flush formulations often intersect with broader coolant and antifreeze value chains, where glycol-linked input dynamics can influence margin planning, price positioning, and inventory strategy.
Phosphoric acid pricing trends further illustrate the regional complexity of formulation input costs. As of March 2026, phosphoric acid prices stood at approximately 1.21 USD per kilogram in North America, up 0.8 percent; 1.37 USD per kilogram in Europe, down 0.7 percent; 1.05 USD per kilogram in Northeast Asia, down 1.9 percent; and 0.87 USD per kilogram in Africa, unchanged. These regional differentials can shape sourcing decisions, export-import competitiveness, and formulation design choices, particularly for acid-based chemistries where acid sourcing and purity profiles influence performance claims, cost structures, and regional price elasticity. The report integrates these raw-material dynamics into formulation-cost modeling and margin-scenario analysis, enabling procurement and product-management teams to map exposure across geographies and product lines.
Regulatory Context and Operational Compliance
Regulatory developments continue to shape how cooling-system maintenance products are positioned, communicated, and deployed within service workflows. U.S. EPA refrigerant management rules under 40 CFR Part 84 Subpart C introduced stricter limits on reclaimed refrigerants, with full effectiveness from January 1, 2026, including restrictions that no refrigerant may be sold as reclaimed if containing more than 15 percent of certain specified substances. While the radiator flushing chemicals market is not directly a refrigerant market, the broader regulatory direction reinforces heightened compliance expectations across automotive cooling-related service categories, including documentation practices, material sourcing integrity, and chemical handling standards.
At the regional level, the California Energy Code 2025 update, effective January 1, 2026, strengthens ventilation standards and expands electric vehicle charging requirements for new buildings. Although this policy does not directly regulate radiator flushing chemicals, it indirectly influences automotive and cooling-system maintenance practices by shaping service-environment standards, facility design expectations, and the broader context in which vehicle servicing and cooling-system care are delivered. These regulatory shifts are examined within the report as part of the operating environment affecting distribution channels, service-provider adoption, and long-term product positioning in regulated markets.
Antifreeze & Coolants Market
What the Market Research Delivers
This Worldwide Radiator Flushing Chemicals Market research is designed to convert market complexity into actionable strategic inputs. Rather than offering a static overview, the report provides a structured intelligence framework covering historical performance from 2020 through 2025, forward-looking forecasts for 2026-2032, and detailed segmentation analysis across product chemistry, vehicle type, and regional demand. The research integrates competitive profiling of core industry participants, formulation-level market positioning, and upstream raw-material monitoring to support both commercial planning and operational decision-making.
Key deliverables include revenue trajectory analysis covering 2020-2032, with explicit focus on the 2026-2032 forecast period and the 5.48 percent CAGR environment that shapes expansion planning. The segmentation component unpacks product chemistry dynamics across acid-based, alkaline-based, and solvent-based categories, alongside vehicle-type demand patterns spanning passenger cars, light commercial vehicles, and heavy commercial vehicles. Regional analysis maps demand intensity and growth positioning across Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa region without oversimplification, enabling country-level prioritization and channel strategy development. Competitive analysis covers core manufacturers with profile depth on product architectures, formulation differentiation, and market presence, supporting benchmarking, competitive response planning, and partnership evaluation. Raw-material monitoring integrates ethylene glycol and phosphoric acid price dynamics into formulation cost exposure and margin planning, while the regulatory context section outlines operating-environment factors that affect compliance posture and service-channel adoption.
To ensure strategic usefulness, the report emphasizes operational interpretation over raw enumeration. Readers will find guidance on where formulation differentiation is most likely to create pricing power, which segments are expanding fastest relative to base markets, how regional cost structures influence competitive positioning, and how leading companies are aligning product portfolios with service-channel expectations. Core segment revenue splits, detailed country-level figures, and full company-level benchmarking tables are reserved for the complete dataset, ensuring that the final research serves as a decision-grade intelligence asset rather than a summary-level briefing.
Implications for 2026 Decision-Making
For organizations planning 2026 initiatives, the market's structural signals point to several strategic priorities. First, formulation performance narratives around corrosion control, deposit removal, system compatibility, and service-speed improvement remain central to competitive differentiation, especially as service providers and fleet operators increasingly weigh maintenance efficiency against total cost of ownership. Second, regional cost exposure and feedstock dynamics should be incorporated into pricing strategy, sourcing decisions, and inventory planning, with attention to regional phosphoric acid differentials and ethylene glycol supply conditions that can influence margin stability across product lines. Third, the balanced competitive concentration profile suggests that both established players and new entrants can influence share dynamics through targeted product positioning, distribution expansion, and service-channel relationship building. Fourth, regulatory and operating-environment developments should be tracked as part of go-to-market planning, particularly where service-environment standards and compliance expectations affect product adoption and channel execution.
The full research report translates these implications into a structured decision framework, enabling leadership teams to assess where to allocate commercial resources, which formulation and segment opportunities warrant deeper investment, and how competitive and supply-side dynamics are likely to shape margin and share outcomes over the 2026-2032 horizon. The complete market sizing dataset, segmentation detail, and proprietary competitive benchmarking are available through the full report, providing the depth required for definitive strategic planning and execution design.
Request access to the full Worldwide Radiator Flushing Chemicals Market research to obtain detailed segment revenues, regional breakdowns, competitive benchmarking matrices, and the complete 2026-2032 forecast model.
For detailed analysis of this topic, please visit the official page: Worldwide Radiator Flushing Chemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Indirect Auto Finance Market to Hit $474 Billion by 2032 at 6.85% CAGR
By PW Consulting, 2026-09-17
Navigating the Indirect Auto Finance Landscape: Strategic Intelligence for 2026 and Beyond
The automotive retail ecosystem is undergoing a structural transformation, and at the center of this shift lies the indirect auto finance market. For executives, investors, and policy strategists, understanding the mechanics of dealer-originated lending is no longer optional. It is a prerequisite for capital allocation, product development, and competitive positioning. Our latest market research delivers a comprehensive, data-rich map of this sector, designed to translate macroeconomic signals and regulatory friction points into actionable decision frameworks for the 2026 to 2032 horizon.
This article serves as a strategic preview of the full study. It outlines the analytical architecture, highlights the most critical market dynamics that will define the next planning cycle, and explains how leadership teams can leverage the full publication to build resilient, forward-looking strategies. While we provide verified high-level metrics and structural insights here, the granular segmentations, competitive benchmarking matrices, and scenario-weighted forecast models remain exclusive to the complete report. Readers seeking the complete intelligence suite are directed to the source page, where the full dataset, interactive visualizations, and executive briefs are available for immediate deployment.
Indirect Auto Finance Market
The Structural Pulse of the Market: Size, Trajectory, and Concentration
Indirect auto finance—where dealerships originate retail installment contracts and dealer floorplan facilities on behalf of third-party lenders—has cemented its role as the dominant distribution channel for vehicle credit. Our historical reconstruction from 2020 through 2025 documents a sector that expanded from approximately 168.45 billion USD in 2020 to 298.5 billion USD in 2025, reflecting both the post-pandemic vehicle procurement surge and the sustained preference for dealer-mediated credit origination. The momentum carries into the forecast window, with the market projected to reach roughly 322.02 billion USD in 2026 and to continue its ascent toward 474.0 billion USD by 2032.
The compound annual growth rate across the forecast period is estimated at 6.85 percent, a pace that signals durable expansion rather than a cyclical rebound. This trajectory is shaped by enduring consumer behavior, dealer economics, and lender appetite for originated credit, even as macro headwinds introduce episodic demand volatility. Industry analysis indicates a modest contraction in overall auto loan originations expected for 2026, driven by affordability constraints and elevated vehicle pricing. Yet indirect channels remain structurally embedded, and the addressable market continues to scale as financing penetration deepens across both new and pre-owned vehicle transactions.
Concentration patterns underscore the strategic importance of channel relationships. The market is moderately consolidated, with the top three participants holding an estimated 38.5 percent share and the top five capturing approximately 52.3 percent. This structure creates a layered competitive field: large captives and scaled banks anchor the prime and near-prime corridors, independent finance companies extend reach into non-prime segments, and dealer networks operate as the critical gatekeepers of origination volume. Understanding how these layers interact—and where margin pools and risk asymmetries emerge—is central to any credible market entry, partnership, or portfolio strategy.
How the Report Is Structured: Turning Complexity into Decision-Ready Intelligence
The full study is built around practitioner needs. Rather than presenting a static snapshot, the report constructs a multi-layered analytical model that links segment dynamics to strategic choices. The architecture is organized to support scenario planning, competitive response design, and risk-weighted growth planning across the 2026 to 2032 period.
At the foundation, the report provides a disciplined segmentation framework that disaggregates the market along operationally meaningful axes. It examines regional dynamics across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, and it separates new vehicle financing from used vehicle financing to reflect different credit profiles, margin structures, and dealer behavior. The application lens distinguishes passenger vehicles from commercial vehicles, capturing divergent underwriting logic, utilization patterns, and lender tolerance for risk. Each dimension is mapped to volume trends, channel economics, and lender positioning, allowing readers to isolate where growth is most durable and where competitive intensity is rising fastest.
Beyond segmentation, the study delivers operational and strategic content designed for immediate use. These include dealer network influence mapping, lender origination economics, underwriting evolution in digital and hybrid processes, floorplan financing dynamics, and lease-versus-loan mix considerations for captives and independents. The report also evaluates channel conflict and cooperation between banks, credit unions, captive arms, and independent finance companies, with specific attention to how dealer partnerships shape approval speed, pricing competitiveness, and customer experience. Where relevant, the analysis connects these themes to portfolio performance indicators, delinquency sensitivities, and the implications of shifting credit standards.
The competitive profiling section does not simply list companies; it situates them within the market’s operational logic. Profiles address corporate footprint, financing philosophy, channel strategy, and competitive differentiation, enabling readers to assess where incumbents are defending share, where they are vulnerable, and where whitespace may exist for new entrants or partnership models. The report balances the perspective of major non-captive providers, captives anchored in manufacturer brands, and large bank-based auto lenders, and it includes specialized independents that target specific credit tiers.
Competitive Architecture: Captives, Banks, and the Independent Layer
The competitive field is best understood as a system of interdependent roles rather than a simple brand ranking. Captive finance arms—organizations tied closely to original equipment manufacturers—operate as strategic instruments of retail impact, brand loyalty, and inventory velocity. Major captives provide indirect financing through their respective dealership networks, combining retail installment contracts with lease options and, in several cases, dealer floorplan support. Their strategic advantage lies in the ability to align financing incentives with brand mix, model lifecycle, and promotional cadence, making them deeply embedded in the commercial logic of vehicle sales.
Finance Lease Market
Non-captive lenders occupy a complementary but distinct position. Large banks and diversified consumer finance institutions leverage dealer relationships to originate indirect auto loans at scale, emphasizing competitive rates, digital approval workflows, and integration with broader retail and commercial banking relationships. These institutions benefit from balance sheet capacity, data infrastructure, and cross-sell potential, and they continue to gain relevance in dealer-originated volume as dealer finance debt expands. Their operational focus increasingly centers on speed of decisioning, omnichannel experience, and risk-based pricing precision.
Independent finance companies add a third dimension to the landscape, often concentrating on non-prime and specialty segments where underwriting nuance and dealer trust are decisive. These players depend on deep relationships with franchise and independent dealerships, flexible contract structures, and targeted credit strategies. Their growth is closely tied to dealer willingness to forward contracts, local market conditions, and the relative cost of funding. In this ecosystem, competitive advantage is less about scale alone and more about channel intimacy, underwriting alignment, and the ability to absorb risk in segments that larger lenders may underweight.
The strategic implication for market participants is clear. Pricing, product design, and origination strategy must be calibrated to the segment, the dealer type, and the credit tier. Market share gains are often won through the quality of dealer partnerships, the reliability of funding, and the credibility of underwriting—not through marketing alone. Leaders need a precise reading of where each competitor is positioned, what channel leverage it holds, and how its economics shift when rate environments, inventory conditions, or regulatory definitions change.
Market Dynamics and the 2026 Decision Environment
Current dynamics are reshaping both opportunity and constraint. A recurring theme across recent industry analysis is the continued dominance of the indirect channel, with a substantial majority of auto loans originated through dealerships that forward contracts to banks, credit unions, and finance companies. This concentration of origination in dealer networks elevates the strategic value of channel relationships and underscores the importance of lender readiness in terms of speed, flexibility, and consistent funding.
At the same time, the distribution of share is evolving. Recent analysis indicates that banks and non-captive lenders are gaining ground in dealer-originated indirect auto loans, with dealer finance debt rising more than 20 percent year-over-year in one widely cited measurement. This trend reflects the interplay of funding availability, underwriting technology, and dealer preferences for lender reliability. It also signals that indirect finance is not a static monopoly of any one category; the market is contested, and competitive positioning can shift as dealers recalibrate their panel of lenders.
Regulatory development is another force that demands strategic attention. Policy activity around nonbank auto finance participants has accelerated, including discussions of larger participant definitions and adjustments to origination thresholds that determine regulatory footprint. Related legal interpretations are also in motion, including guidance that affects how disparate impact claims are understood under fair lending frameworks. These developments do not merely create compliance obligations; they alter the calculus of market entry, product design, portfolio scaling, and the cost of operating across prime and non-prime segments. Organizations that build regulatory foresight into their planning will be better positioned to adapt product structures, risk appetite, and geographic footprint without losing momentum.
Consumer affordability and price levels introduce a further layer of complexity. Forecasts for 2026 point to a modest decline in overall auto loan originations, reflecting affordability pressure and elevated car prices. This environment rewards precision: lenders and dealers that rely on broad-volume assumptions may find that marginal growth requires sharper segmentation, more granular pricing, and more disciplined risk selection. For captives, the challenge includes managing mix, incentives, and lease penetration in a way that protects both retail demand and portfolio health. For independents, the challenge is to maintain dealer loyalty and credit performance in segments where rate sensitivity and repayment risk move together.
Why This Research Matters for 2026 Strategy
The strategic value of the full report lies in its ability to convert a complex, multi-actor environment into a usable operating map. For leadership teams, the study answers several questions that directly influence 2026 decisions.
- Where is durable growth most likely to come from across regions, vehicle types, and application segments, and how should capital and product effort be prioritized accordingly?
- How should organizations interpret the evolving balance between captives, banks, credit unions, and independent lenders when designing partnership strategies, dealer panels, and origination targets?
- What operational capabilities are most decisive in a market where digital approval, dealer trust, funding stability, and risk-based pricing determine competitive outcomes?
- How do regulatory shifts around larger participant definitions, origination thresholds, and fair lending interpretation change the risk-reward calculus for scaling portfolios or entering new segments?
- In an environment of affordability constraints and elevated vehicle prices, how can organizations protect volume while preserving credit quality and dealer relationships?
These are not abstract questions. They shape pricing strategy, underwriting policy, channel investment, technology roadmaps, and portfolio construction. The report provides the analytical depth needed to answer them with less uncertainty, while deliberately keeping the most granular segmentations and quantitative models in the full publication so that readers can benchmark against their own internal assumptions and test multiple strategic scenarios.
Conclusion: From Market Awareness to Market Advantage
Indirect auto finance remains a market defined by channel power, lender differentiation, and continuous regulatory evolution. The sector’s size and growth trajectory confirm its strategic importance, while the competitive composition and current dynamics reveal where advantage is being created and where risk is accumulating. Organizations that approach 2026 with a clear view of these forces will be better equipped to allocate resources, structure partnerships, and manage exposure across credit tiers and geographies.
This preview has outlined the landscape, the report architecture, and the decision themes that matter most. To access the complete market sizing, the full segmentation analysis, detailed competitive profiles, scenario-based forecasting, and operational recommendations, we invite you to visit the source page for the Indirect Auto Finance Market research. The full study is designed to be used directly in strategy sessions, portfolio reviews, and investment planning, giving decision-makers the granularity they need to move from interpretation to execution.
For detailed analysis of this topic, please visit the official page: Indirect Auto Finance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Digital Cultural Tourism Market to Reach $26.45B in 2025, CAGR 17.6% to 2032
By PW Consulting, 2026-09-17
Navigating the Future of Experience: Strategic Insights into the Worldwide Digital Cultural Tourism Market 2026–2032
The convergence of cultural heritage preservation and digital innovation has moved beyond experimental pilot programs to become a central pillar of global tourism strategy. As destinations, institutions, and experience providers seek to expand reach, deepen engagement, and future-proof operations against physical and environmental constraints, digital cultural tourism has emerged as a high-growth, high-impact sector. Our latest comprehensive market research, Worldwide Digital Cultural Tourism Market, offers a rigorous, data-backed roadmap for executives navigating this rapidly evolving landscape. Designed for strategic decision-makers in 2026, the study translates complex market signals into actionable intelligence, enabling organizations to allocate capital, shape partnerships, and position themselves ahead of structural shifts rather than reacting to them.
Macro Trajectory: A Market Accelerating on Sustained Demand
The foundational numbers tell a compelling story of sustained expansion. Drawing on historical baselines from 2020 through 2025 and projecting forward across the 2026–2032 forecast window, the worldwide digital cultural tourism market has demonstrated consistent compound growth. The sector was valued at approximately 12.45 billion USD in 2020, climbed to 17.01 billion USD by 2022, and reached 26.45 billion USD in the most recent base year, 2025. Looking ahead, the market is projected to breach 31.85 billion USD in 2026 and continue its upward trajectory to exceed 82 billion USD by 2032. This translates to a compound annual growth rate of 17.6 percent over the forecast period, signaling robust, compounding demand rather than a transient post-pandemic rebound.
For 2026 decision-making, this trajectory carries immediate operational implications. Investments made today will compound over the next seven years, and the pace of adoption suggests that organizations establishing digital cultural infrastructure, content pipelines, and platform partnerships now will capture significant first-mover advantages in audience acquisition and revenue diversification. Conversely, delayed positioning risks higher entry costs, saturated competitive niches, and diminished leverage in platform negotiations.
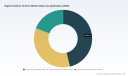
The growth is not uniform across all vectors. Regional momentum, solution adoption curves, and application-specific utilization patterns reveal distinct structural preferences that shape where capital and engineering resources deliver the highest returns. While granular regional and application-level breakdowns are detailed in the full report, the overall market composition reflects a balanced but increasingly differentiated ecosystem. Digital platforms and smart services, immersive experience technologies, and content digitization and management frameworks each command substantial shares of total revenue, with museums and heritage sites, themed parks and cultural centers, and online cultural exhibitions and events representing the primary demand anchors. Understanding how these layers intersect—and where friction, latency, or monetization gaps emerge—forms the analytical backbone of the research.
What the Report Delivers: An Operational Blueprint for 2026 Strategy
This study is engineered to move beyond high-level trend commentary and provide executable strategic frameworks. The report architecture is built around decision-ready modules that map directly to corporate planning cycles. Each section is calibrated to answer the questions that actually drive boardroom and executive team deliberations: where is demand concentrating, what technologies are transitioning from proof-of-concept to scale, which partnership models are proving durable, and how should organizations sequence investments across capability building, content acquisition, and platform deployment?
The analysis integrates historical performance data with forward-looking scenario modeling, allowing readers to stress-test assumptions against varying adoption speeds, regulatory shifts, and technology cost curves. Qualitative insights are grounded in observed industry behavior, documented project deployments, and structural changes in consumer engagement patterns. The research also maps the ecosystem of enablers, from spatial scanning and digital twin infrastructure to generative AI content pipelines and cloud-based virtual exhibition architectures, clarifying which components are becoming commoditized and which remain differentiated sources of competitive advantage.
Beyond market sizing and segmentation, the report examines the interplay between content ownership, platform distribution, and experiential design. It evaluates how institutions and commercial operators are structuring digital asset lifecycles, managing quality assurance, and aligning virtual engagement strategies with on-site visitation philosophies. The objective is to provide a coherent operating model that balances preservation imperatives, audience accessibility, and sustainable monetization without sacrificing authenticity or cultural integrity.
Competitive Landscape: Key Players and Strategic Positioning
The market is shaped by a mix of technology platform providers, immersive experience specialists, heritage-focused documentation organizations, and AI-driven content creators. Rather than operating in isolated silos, these players are increasingly intersecting across data capture, asset generation, distribution, and end-user engagement. The research profiles the core companies that are defining the competitive frontier and analyzes how their capabilities translate into market leverage.
Worldwide Digital Cultural Tourism Market
Worldwide Culinary Tourism Market
Google Arts and Culture has established a foundational role in democratizing access to cultural collections, offering virtual tours, high-resolution imagery, 360-degree videos, and VR experiences across thousands of partner institutions. Its scale and partnership network make it a reference point for how broad distribution can coexist with institutional branding. YouVisit complements this model by focusing on interactive 360-degree virtual experiences and layered media production for museums, heritage locations, and cultural sites, using panoramas, drone footage, and structured narrative design to drive engagement and access.
On the infrastructure and capture side, Matterport has become synonymous with 3D spatial scanning and digital twin creation, enabling museums, historical buildings, and cultural attractions to produce precise, navigable virtual environments. ARCTUR, operating from the European cultural heritage ecosystem, drives the development of the 3D-4CH cultural heritage platform, providing 3D digitization tools, competence centers, and training pipelines designed to standardize digital preservation and virtual access across European assets. CyArk approaches the space from a preservation-first angle, using 3D laser scanning and documentation to create digital archives and virtual tours of at-risk heritage sites, balancing public access with long-term archival resilience.
The competitive frontier is also expanding through generative AI and 3D digital asset specialization. Global Mofy AI Limited has positioned itself at the intersection of AI-driven content creation and immersive exhibition design, delivering digital exhibition halls and virtual content for cultural tourism projects, including ecology- and heritage-themed experiences. Its recent deployments illustrate how cloud-based virtual exhibition infrastructure and AI-assisted production pipelines are moving from concept to operational reality.
These players are not competing solely on technology; they are competing on ecosystem reach, content partnerships, data interoperability, and the ability to scale while preserving cultural fidelity. The report dissects these dynamics in detail, identifying which capabilities are likely to consolidate market power and which niches will remain open to specialized entrants.
Market Dynamics and 2026 Catalysts
Several structural developments are accelerating the strategic relevance of digital cultural tourism in the current planning cycle. A landmark partnership agreement between UNESCO and UN Tourism, signed in March 2026, underscores a coordinated push toward sustainable, inclusive, and resilient tourism with explicit emphasis on cultural heritage protection and digital transformation for virtual access. The agreement includes country-level pilot projects, signaling that policy alignment and institutional cooperation will increasingly shape deployment priorities and funding pathways.
At the regional infrastructure level, the EU 3D-4CH project, led by ARCTUR, launched the 3D Online Competence Centre for cultural heritage in early 2026. This initiative establishes a collaborative ecosystem for 3D data access, enrichment, and reuse, aimed at improving interoperability across digital cultural tourism applications. In parallel, the project hosted its Winter School 2026 in Brussels, focusing on 3D innovation, strategy, and practical applications for heritage digitization. These developments point to a maturing standards environment in which data reuse, cross-institutional collaboration, and workforce capability building are becoming central to scalable deployment.
On the technology deployment side, recent project launches demonstrate the operationalization of cloud-based virtual exhibition infrastructure and AI-driven reconstruction techniques. The opening of an immersive digital exhibition hall at a scenic area in partnership with a cultural tourism group illustrates how ecological conservation themes and heritage experiences are being translated into digital environments that support both public engagement and preservation narratives. Such deployments reinforce the shift from one-off virtual experiences to repeatable, infrastructure-backed service models.
For decision-makers, these dynamics carry three immediate implications. First, interoperability and data standards are becoming strategic assets rather than optional technical considerations. Second, institutional partnerships and policy-aligned pilots are opening new avenues for co-investment and deployment scale. Third, the convergence of generative AI, spatial capture, and cloud exhibition infrastructure is compressing timelines from concept to launch, raising the stakes for organizations that delay capability development.
Implications for 2026 Decision-Makers
The market’s growth profile and competitive structure call for a disciplined, sequenced approach to strategy. Organizations should evaluate digital cultural tourism not as a standalone marketing channel but as an integrated capability that connects audience acquisition, content lifecycle management, platform distribution, and on-site experience design. The following strategic priorities emerge as particularly relevant for 2026 planning:
- Align investment with demand anchors. Museums, heritage sites, themed parks, cultural centers, and online exhibitions each exhibit distinct user expectations and monetization pathways. Prioritization should reflect both audience fit and operational readiness rather than market noise.
- Treat data and interoperability as strategic assets. Multiuse 3D assets, standardized enrichment pipelines, and reusable digital archives reduce marginal cost over time and increase partnership leverage. Building for reuse from the outset improves long-term ROI.
- Sequence capability building before scale. Spatial capture, digital twin management, AI-assisted content production, and platform distribution each require distinct competencies. Organizations that sequence talent, vendor selection, and workflow design before large-scale deployment avoid costly rework.
- Anchor virtual experiences in preservation and authenticity. Digital access expands reach, but audience trust and institutional credibility depend on how faithfully experiences represent cultural context. Quality assurance and narrative integrity should be treated as core performance metrics.
- Leverage institutional and policy alignment. Emerging cooperation frameworks and pilot programs can de-risk deployment and unlock co-investment. Early engagement with aligned initiatives can accelerate access to data, standards, and distribution networks.
Why This Research Matters Now
The digital cultural tourism market is entering a phase where growth is sustained, infrastructure is maturing, and competitive differentiation increasingly depends on execution quality rather than technology novelty alone. In this environment, high-level sentiment is insufficient. Decision-makers need granular segmentation, benchmarked competitive profiles, deployment readouts, and scenario-based guidance that connects market data to operational choices.
The full Worldwide Digital Cultural Tourism Market research report provides that depth. It presents detailed segmentation analysis, historical and forecast trajectories, competitive positioning frameworks, recent development timelines, and operational recommendations calibrated for executive planning. The complete dataset, regional and application-level breakdowns, and enterprise-level strategic implications are available through the full report, which is designed to serve as a reference point for market entry, investment allocation, partnership strategy, and technology roadmap development.
For teams preparing 2026 strategies, the opportunity window is narrow and accelerating. Organizations that access the complete market intelligence now can move with clarity on where demand is forming, which capabilities are becoming essential, and how to structure engagements that compound value across the forecast horizon. The full report is the most direct path to that precision.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Cultural Tourism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Digital Movie Projector Market to Hit $7.18B by 2032, 7.21% CAGR
By PW Consulting, 2026-09-17
Strategic Intelligence for the Next Era: Inside the Worldwide Digital Movie Projector Market Research
The global cinema exhibition landscape is undergoing a structural transformation. As exhibition chains navigate post-recovery attendance patterns, technology refresh cycles, and escalating content quality expectations, the digital movie projector market has emerged as a critical battleground for competitive positioning, capital allocation, and long-term commercial strategy. PW Consulting recent comprehensive study on the Worldwide Digital Movie Projector Market delivers a rigorously validated, forward-looking intelligence framework designed specifically for enterprise decision-makers operating in 2026 and beyond. This market research introduction outlines the strategic architecture of the report, highlights the market mechanics that will define competitive outcomes, and demonstrates how leadership teams can translate macro momentum into executable growth strategies.
The analysis spans a five-year historical baseline from 2020 through 2025, extended by a seven-year forecast horizon reaching 2032. This temporal architecture enables stakeholders to calibrate investment cycles, anticipate supply chain inflection points, and evaluate how exhibition infrastructure rollouts align with broader content distribution roadmaps. By anchoring strategic planning in validated historical trajectories and systematically modeled forward scenarios, the report equips executives with the analytical discipline required to navigate an industry characterized by rapid technological substitution and evolving geographic demand patterns.
Macro Market Trajectory and the Strategic Imperative for 2026
The worldwide digital movie projector market has demonstrated sustained expansion across the analyzed historical window. Revenue scaled from approximately 1,850.4 million USD in 2020 to 4,412.5 million USD by the 2025 base year, reflecting a decisive shift in global exhibition infrastructure as traditional lamp-based systems gave way to higher-efficiency illumination architectures and exhibitors modernized screens to meet premium format requirements. The market is projected to continue its upward trajectory through the forecast period, reaching 7,183.43 million USD by 2032, supported by a compound annual growth rate of 7.21 percent.
For executive teams, this growth profile carries several strategic implications. First, the expanding addressable market signals that capital deployment into projection technology is no longer a maintenance exercise but a growth-oriented investment. Second, the pace of expansion creates a competitive window for manufacturers and system integrators to capture share before market saturation intensifies in mature exhibition corridors. Third, the forecast horizon underscores the importance of modular product roadmaps, as exhibitors increasingly demand flexible deployment architectures that accommodate varying screen sizes, ambient light conditions, and operational budgets.
Amid this trajectory, industry participants must also contend with structural dependencies that influence supply resilience and cost structuring. High-performance laser diodes and solid-state laser components rely on rare earth materials, with concentrated sourcing networks introducing potential vulnerabilities into manufacturing pipelines. Simultaneously, standardized technology licensing frameworks shape which manufacturers can commercially deploy certain digital cinema architectures, reinforcing industry concentration and influencing partnership strategies. Decision-makers who model these dependencies explicitly will be better positioned to secure component availability, negotiate supplier terms, and design product portfolios that remain viable under shifting raw material dynamics.
Report Architecture: Actionable Intelligence for Executive Decision-Making
The research is structured to convert complex market signals into operational clarity. Rather than presenting abstract market summaries, the publication delivers a multi-layered intelligence framework that supports pricing strategy, R&D prioritization, regional rollout planning, and partnership evaluation. The report content is designed for cross-functional use, enabling product leadership, commercial teams, and strategy offices to align around a unified evidence base.
Core analytical components include:
- A detailed historical reconstruction of market performance across key valuation years, enabling trend validation and scenario anchoring
- A forward-looking forecast model extending through the end of the decade, with explicit assumptions around adoption pacing, technology transitions, and exhibition upgrade cycles
- A structural segmentation analysis that disentangles the primary commercial axes shaping demand, allowing stakeholders to isolate growth drivers and assess portfolio fit across distinct product architectures
- A competitive positioning review that examines strategic moves by leading manufacturers, highlighting product launches, technology introductions, and market expansion patterns that indicate where industry momentum is accumulating
- A qualitative and quantitative assessment of market concentration, providing context for pricing power, barrier-to-entry dynamics, and partnership considerations
- An integrated review of technology dependencies, regulatory and licensing frameworks, and supply chain sensitivities that can materially affect cost structures and deployment timelines
Each analytical module is engineered to support concrete decision-making. Exhibitors can use the findings to sequence capital upgrades across venue portfolios. Manufacturers can identify where next-generation illumination systems and resolution formats are gaining traction relative to legacy configurations. Component suppliers and service providers can map demand patterns to anticipate aftermarket service needs, maintenance cycles, and retrofit opportunities. By maintaining consistency between historical analysis and forward projection, the report reduces ambiguity in budgeting and strategic planning, allowing organizations to commit resources with greater confidence.
Competitive Architecture and the Battle for Next-Generation Projection
The digital cinema projector market is characterized by a concentrated supplier base, with leading manufacturers controlling a substantial share of global revenue. Recent competitive activity demonstrates how incumbents are reinforcing their positions through illumination innovation, format differentiation, and targeted geographic expansion. Understanding these moves is essential for any organization evaluating partnership opportunities, competitive response strategies, or product development priorities.
Digital Light Processing (DLP) Projector Market
Barco NV continues to position itself as a leading provider of laser-based digital cinema projectors, emphasizing unified next-generation product families that balance performance with operational simplicity for commercial theaters. Its focus on high-brightness RGB laser systems reflects a broader industry shift toward illumination architectures that enhance color volume, consistency, and brightness stability across varied screening environments. Christie Digital Systems maintains a strong presence through its high-performance cinema portfolio, including the CineLife+ series and RGB laser platforms designed for diverse screen sizes. The company has also built recognition around advanced HDR and Dolby Vision-aligned solutions, reinforcing its association with premium image performance and award-recognized engineering.
NEC Display Solutions, operating through Sharp NEC, delivers digital cinema projectors built on DLP technology, prioritizing high brightness and extended operational lifespan for theatrical deployments. Sony Corporation remains active in professional projection ecosystems, bringing SXRD and DLP lineage to high-end cinema contexts while adjusting its portfolio footprint in response to broader segment evolution. The strategic behavior of these firms illustrates a market where differentiation increasingly depends on illumination technology, optical performance, service infrastructure, and the ability to align hardware with emerging content delivery standards.
Recent corporate activity reinforces the pace of innovation. In January 2025, Christie Digital introduced new CineLife+ RBe series projectors featuring Phazer illumination technology designed to improve image performance on small, high-gain screens, alongside Jazz Series 1DLP laser projectors built around Texas Instruments 0.8-inch HEP DMD components for improved color, contrast, and a more compact chassis. Later that year, Christie expanded its cinema lineup with RGBH projectors using CineLife+ electronics and Phazer illumination for small to mid-size screens. In January 2026, Texas Instruments showcased new DMD chipsets and controllers enabling higher brightness, improved native contrast, 4K/120 fps support, and compact high-lumen projector designs at CES 2026. These developments signal an industry moving rapidly toward higher resolution, higher brightness, and more efficient optical architectures, while also compressing form factors to support flexible installation scenarios.
Alongside product momentum, regulatory and technical licensing structures continue to shape competitive boundaries. DLP Cinema technology for digital cinema projectors is licensed by Texas Instruments primarily to Barco, Christie, and NEC, reinforcing a linked ecosystem of hardware developers operating under shared optical and digital standards. At the same time, laser illumination systems accounted for an estimated 55 to 68 percent of cinema projector shipments from major manufacturers in 2025, highlighting how quickly illumination technology is reshaping shipment composition and buyer preferences.
Technology Transitions, Critical Materials, and Regional Demand Signals
Technology migration is one of the most consequential forces shaping product strategy. The shift from xenon lamp projection toward laser projection is not simply a performance upgrade; it reflects a broader reconfiguration of total cost of ownership, maintenance intervals, brightness stability, and content compatibility. As exhibitors evaluate whether to replace legacy units or expand screen capacity, the choice of light source becomes a strategic decision with implications for energy consumption, service logistics, and long-term operational expenditure.
Resolution format adoption further complicates the decision environment. High-resolution projection is increasingly associated with premium large-format experiences, upgraded contractual expectations from studios, and audiences accustomed to higher detail levels. As 4K-class formats gain share relative to 2K configurations, manufacturers and exhibitors must consider how product roadmaps align with content pipelines, screen dimensions, and budgetary constraints. This transition is not uniform across all venue classes, which makes segmentation-based planning essential for identifying where premium upgrades will generate the strongest return and where cost-efficient reliability remains the primary buying criterion.
Supply-side resilience is equally important. The dependency on rare earth materials within high-performance laser diode and solid-state laser supply chains introduces concentration risk that can affect lead times, pricing, and continuity of supply. Organizations that incorporate supplier diversification, inventory buffering, and long-term sourcing agreements into their strategy are better insulated against volatility. This is particularly relevant for manufacturers scaling laser-based portfolios and for exhibitors planning multi-year upgrade programs that depend on predictable equipment availability.
Regional demand patterns add another layer of strategic complexity. While mature exhibition markets continue to refresh installed bases and pursue premium format upgrades, select growth regions are accelerating infrastructure build-out through large-scale procurement initiatives. Geopolitical and national development programs can generate concentrated demand spikes, creating both opportunity and execution risk. For example, Vision 2030 initiatives in Saudi Arabia have driven significant demand for laser DLP cinema projectors, with Christie securing a contract for more than 420 units in early 2026. Such developments illustrate how government-backed entertainment and tourism objectives can abruptly reshape regional procurement priorities, rewarding manufacturers and partners capable of delivering at scale with technical compliance and localized support.
Strategic Applications of the Research for 2026 Decision-Making
The strategic value of this research lies in its ability to convert market complexity into decision-ready intelligence. For manufacturing leadership, the report supports product portfolio calibration, helping teams determine where to emphasize laser illumination development, resolution upgrades, and compact high-brightness architectures. For exhibition operators, it informs venue-level upgrade sequencing, enabling smarter prioritization of screens that will generate the strongest audience response and revenue uplift from new projection systems. For investors and corporate strategy teams, it provides a structured view of concentration dynamics, competitive moats, and technology dependency risks that influence valuation assumptions and partnership selection.
In practice, the research can be applied across several critical planning dimensions:
- Assessing whether near-term capital should prioritize new product introductions, service expansion, or market-specific geographic development
- Identifying which technology transitions are moving from early deployment to mainstream adoption and how quickly incumbent portfolios must adapt
- Evaluating competitive vulnerability in segments where illumination, resolution, or brightness leadership is becoming a decisive purchase factor
- Modeling supply chain exposure related to laser components and rare earth dependencies, then aligning procurement and production strategies accordingly
- Interpreting regional demand signals to determine where large-scale opportunities may emerge and what local support, certification, or partnership capabilities are required to win
By connecting historical performance, forward forecast logic, and competitive activity in one integrated analysis, the study helps organizations avoid fragmented decision-making. Instead of reacting to individual product launches or isolated regional orders, executives can evaluate how multiple forces interact and shape the next cycle of market leadership.
Why the Full Report Matters Now
Market intelligence is most valuable when it does more than describe what has already occurred. It must clarify what is likely to happen, where competitive advantage will be created, and which decisions should be made before the market reallocates share. The Worldwide Digital Movie Projector Market research is designed to meet that standard. It integrates validated historical data, a disciplined forecast framework, and a detailed review of technology, competitive, and regional dynamics into a single strategic reference point.
Because the full report contains the segmented breakdowns, detailed scenario assumptions, competitive benchmarking, and operational recommendations that executive teams need to build precise plans, it is structured as a comprehensive decision-support asset rather than a high-level summary. Readers who require exact regional valuations, application-level market allocations, and granular resolution- and light-source-level insights will find the complete dataset essential for pricing, forecasting, and investment decisions.
Worldwide Digital Movie Projector Market
For leadership teams preparing for 2026 and the forecast years ahead, the complete research delivers the level of clarity required to act with confidence. The market is expanding, the technology base is shifting, and competitive intensity is rising. Organizations that ground their strategy in rigorous, forward-looking intelligence will be best positioned to capture growth, manage supply and technology risk, and build durable advantage in a rapidly evolving exhibition technology landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Movie Projector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Dispute & Arbitration Market to Hit USD 38,238.2 Million by 2032
By PW Consulting, 2026-09-17
The Global Dispute Advisory and International Arbitration Market 2026–2032: Strategic Intelligence for Enterprise Decision-Making
The mechanics of global commerce are shifting beneath the feet of corporate boards. Disputes that once settled in regional courts now traverse continents, implicate sovereign interests, and unfold under increasingly complex digital and regulatory architectures. For enterprises operating across borders, the question is no longer whether disputes will arise, but how quickly, how expensively, and under what procedural conditions they will be resolved. PW Consulting's Worldwide Dispute Advisory and International Arbitration Market research, newly released and anchored in a comprehensive dataset spanning 2020 through a forecast period extending to 2032, offers a structured, evidence-based vantage point for executives navigating this terrain. This article previews the strategic architecture of the report, outlines the operational intelligence it contains, and explains why the 2026 decision window demands more than intuition.
A Market in Structured Expansion: Reading the Trajectory
The global dispute advisory and international arbitration market has completed a sustained growth cycle and is entering a phase of accelerated maturity. Drawing on historical records from 2020 through the base year of 2025 and extending forecast projections to 2032, the study maps a revenue trajectory that reflects both organic demand expansion and the structural professionalization of dispute resolution services. Over the historical window, the market advanced from approximately 18.25 billion to 24.85 billion, demonstrating a compound trajectory that outpaces general professional services benchmarks. The forward view projects further expansion through 2032, with the overall market scale anticipated to climb meaningfully as cross-border transaction volumes, infrastructure commitments, and energy-sector investments continue to generate complex, multi-party disputes.
At the core of the forecast lies a compound annual growth rate of 6.35 percent across the projection horizon. This rate is not a generic curve fitted to sector averages; it is derived from institutional filing patterns, jurisdictional diversity indicators, service-type demand shifts, and regional deployment dynamics documented throughout the historical period. For strategy and finance leaders, the implication is clear: annualized planning for dispute-related contingencies, external counsel budgeting, and risk advisory partnerships must account for a market that is consistently appreciating rather than fluctuating at the mercy of discrete case spikes. The report embeds this trajectory within sensitivity overlays that account for jurisdictional case-load variability, macroeconomic stress scenarios, and shifts in institutional rule-making, providing decision-makers with a disciplined range rather than a single-point estimate.
What the Report Delivers Beyond the Top-Line Numbers
Market size and growth rates are necessary scaffolding, but they are not the substance of strategic action. The research is built around actionable intelligence designed to translate market movement into internal planning, vendor selection, and risk posture adjustments. The report structure spans multiple analytical dimensions that practitioners can operationalize immediately.
The service-type analysis dissects demand across forensic accounting and damage valuation, technical and delay analysis, legal advisory and counsel, and strategic advisory and risk management. Each category is examined not as an isolated line item but as a function of dispute complexity, evidentiary burden, and the procedural stage at which organizations most frequently seek external support. The sectoral breakdown maps activity across construction and infrastructure, energy and natural resources, banking and financial services, technology and telecommunications, and a residual category capturing emerging and cross-cutting engagements. This vertical lens is paired with regional deployment patterns that reveal where institutional seats, party domiciles, and expert networks are concentrated, allowing enterprises to calibrate geographic resource allocation against their own transaction footprints.
Beyond segmentation, the report integrates procedural and structural intelligence that frequently escapes generic market summaries. The analysis incorporates developments in data privacy and cybersecurity governance within arbitration contexts, including the application of frameworks such as GDPR Article 32 and guidance from joint task forces addressing electronic evidence and confidentiality obligations. It also examines how specialized human capital, seasoned arbitration counsel and subject-matter experts, continues to function as a primary operational cost driver, and how leading practices are responding through integrated global teams designed to manage high-value, multi-jurisdictional matters more efficiently. These threads are not decorative; they form the connective tissue between market scale and the practical mechanics of dispute readiness.
Competitive Architecture and the Cost of Positioning
The international arbitration ecosystem is defined by a distinctive concentration pattern. The market is not dominated by a handful of overwhelming incumbents; rather, it reflects a moderately fragmented structure in which concentrated leadership coexists with deep specialization across boutiques, global full-service practices, and advisory firms that bring forensic, valuation, and expert-witness capabilities into arbitration contexts. The research documents this arrangement through concentration indicators that illustrate the share of activity captured by leading firms, revealing a landscape where scale advantages in cross-border case management exist alongside highly differentiated practice strengths in energy, infrastructure, investor-state, and commercial treaty matters.
Several firms anchor this competitive field, each with identifiable strategic positioning. Freshfields Bruckhaus Deringer operates with a pronounced emphasis on pre-contentious strategic advice and representation across major institutions, with distinctive depth in energy, infrastructure, and public international law. White & Case maintains a global arbitration platform covering commercial, investor-state, and enforcement proceedings, complemented by recurring user-preference research that informs how parties experience institutional processes. Herbert Smith Freehills Kramer delivers integrated global arbitration services with particular momentum in Asia-Pacific high-value mandates spanning energy, construction, and corporate sectors. King & Spalding continues to specialize in arbitration and litigation for energy, infrastructure, and commercial disputes, frequently positioned among top-tier global practices in both commercial and treaty work.
Debevoise & Plimpton's profile reflects high-value commercial and investor-state representation with recognized strength in energy sector disputes and public international law. Three Crowns LLP operates as a boutique exclusively focused on international arbitration and public international law, providing counsel and advocacy in high-stakes matters where procedural precision is paramount. Quinn Emanuel Urquhart & Sullivan has been recognized for its international arbitration representation across commercial, construction, energy, and sovereign disputes, reflecting a practice built around intensive advocacy under major institutional rules. Baker McKenzie offers a full-range arbitration advisory and representation platform covering investor-state, commercial, energy, mining, and post-M&A disputes across a broad geographic network. Squire Patton Boggs brings strength in energy, commodities, and investment treaty arbitrations, while Cleary Gottlieb Steen & Hamilton contributes both complex cross-border dispute handling and recurring analytical publications on arbitration trends, including emerging issues such as artificial intelligence and tariff-related disputes. PwC's dispute advisory footprint, encompassing forensic analysis, valuation, expert witness support, and strategic advice, completes the competitive picture by illustrating how accounting and advisory capabilities intersect with legal advocacy in arbitration contexts.
The report does not stop at firm profiles. It maps how these players interact with institutional activity, jurisdictional preferences, and service-type demand shifts, allowing enterprises to assess not only who is active but where capability aligns with the nature of their likely exposure.
The 2026 Context: Forces Reshaping Dispute Resolution Decision-Making
The most valuable intelligence in a market study is not merely where the market has been, but what is changing in real time. A series of recent institutional and practice-level developments illustrates the tempo of transformation that the 2026 decision window must accommodate.
At the institutional level, preliminary statistics released in early 2026 show that international dispute resolution continues to operate at exceptional scale and geographic breadth. One major arbitral institution reported 881 new cases filed under its arbitration rules in the prior year, with more than 2,500 parties originating from 147 jurisdictions and procedural seats located across 123 cities in 70 countries, alongside an aggregate pending case value approaching 299 billion. These figures are more than institutional metrics; they signal a dispute environment in which party diversity, multi-seat logistics, and high aggregate exposure are structural features rather than temporary anomalies. Complementary reporting from another leading arbitral institution showed similarly international patterns in its casework, with the substantial majority of cases involving parties from more than 100 jurisdictions, reinforcing the globalized character of contemporary arbitration practice.
eDiscovery Market
Rankings and recognition developments further clarify competitive standing while highlighting the criteria by which market participants are evaluated. Chambers and Partners' 2026 global rankings recognized multiple firms and individuals as market leaders or top-tier practitioners in international arbitration, with named recognition for firms including White & Case and King & Spalding. Industry awards have likewise highlighted specific practices for sustained excellence; one firm received International Arbitration Team of the Year recognition at a major UK awards program for its global practice in complex disputes. These recognitions, while not substitutes for fit assessment, provide a structured reference point for understanding where institutional credibility and peer evaluation converge.
Equally significant are the thematic forces now reshaping arbitration workflows. Macroeconomic and geopolitical turbulence continues to elevate cross-border friction, while technological breakthroughs, particularly the integration of artificial intelligence for case analysis and evidence review, are altering how disputes are prepared, managed, and adjudicated. Cleary Gottlieb's 2026 trends analysis documents a surge in commercial arbitrations, renewed attention to enforcement against sovereigns, and the growing salience of tariff-related disputes alongside cryptocurrency and regulatory questions. At the same time, emerging guidance on data protection, including the work of joint task forces addressing electronic evidence and confidentiality within arbitration, underscores that procedural compliance is becoming as strategically consequential as substantive advocacy. ESG considerations are also exerting greater influence on dispute posture, stakeholder expectations, and the reputational calculus surrounding resolution choices.
Translating Intelligence into 2026 Enterprise Decisions
For boards, general counsel, risk leaders, and corporate development teams, the strategic value of this research lies in its capacity to convert market behavior into decision architecture. The report is designed to support several concrete planning functions that 2026 demands.
Worldwide Dispute Advisory and International Arbitration Market
First, it enables more disciplined external engagement strategy. By linking service-type demand to sectoral exposure and regional deployment, enterprises can align counsel selection, forensic and valuation partnerships, and strategic advisory retainers with the dispute profiles most likely to arise from their transaction portfolios. Second, the concentration and competitive analysis supports vendor diversification and escalation planning, helping organizations avoid over-reliance on any single practice cluster while identifying where integrated global teams and boutique specialization each offer distinct advantages. Third, the institutional and procedural intelligence provides a basis for calibrating internal dispute readiness: evidentiary protocols, data-handling standards, cross-border seat considerations, and the operational implications of AI-assisted review and tariff-related compliance questions can be anticipated rather than improvised after a filing has begun.
The study also frames cost and timeline expectations more realistically. Because specialized human capital remains a primary cost driver, and because institutional activity continues to reflect high internationality and high aggregate exposure, enterprises benefit from modeling dispute-related expenditure as a recurring strategic line item rather than an episodic surprise. The report's forward trajectory, embedded in sensitivity analysis and anchored by historical-to-forecast continuity, gives finance and legal leadership a defensible basis for budgeting, reserving, and insurance calibration across the 2026–2032 window.
Where the Full Intelligence Resides
This overview establishes the why and the how of the report, but the decisive detail lives in the complete analysis. The full PW Consulting Worldwide Dispute Advisory and International Arbitration Market research contains the segmented operational breakdowns, the jurisdictional and institutional mappings, the competitive positioning matrices, and the forward scenario overlays that executives need to operationalize the themes summarized here. The report's segmentation detail, service-type dynamics, vertical demand distribution, and regional deployment patterns are presented with the granularity required for hands-on planning, while the concentration structure and firm-level profiles are analyzed in relation to service fit, geographic reach, and procedural capability rather than as static rankings.
For decision-makers preparing for the 2026 operating year and the forecast horizon beyond it, the complete study functions as a reference system for external engagement design, risk budgeting, and dispute-readiness investment. The macro trajectory and the 2026 institutional and practice developments provide the context; the full segmentation, concentration analysis, and firm-specific intelligence provide the decision-grade depth. PW Consulting has structured the research to support precisely that transition from awareness to action, and the complete report is available for teams that need to move from strategic overview to implementation-ready insight.
For detailed analysis of this topic, please visit the official page: Worldwide Dispute Advisory and International Arbitration Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PCM Metal Sheet Market to Hit $4.85B in 2025, Grow at 5.15% CAGR Through 2032
By PW Consulting, 2026-09-17
Navigating the 2026 Landscape: A Strategic Introduction to the Pre-Coated Metal (PCM) Sheet Market
The global Pre-Coated Metal (PCM) sheet market stands at a critical inflection point as we move through 2026. For executives, procurement leaders, and strategic planners, the ability to anticipate shifts in substrate pricing, coating technologies, and regional demand trajectories is no longer a luxury—it is a fundamental requirement for maintaining competitive advantage. This article serves as a strategic preview of our newly released comprehensive market research, offering a high-level view of the market forces defining the period from 2026 to 2032. The full report provides the granular intelligence necessary to transform these macro trends into actionable business decisions.
Our analysis is anchored in a robust historical framework spanning 2020 to 2025, which allows us to validate growth patterns and identify structural breaks before projecting forward. The market has demonstrated persistent expansion over this period, evolving from a base valuation of approximately 3,750.25 million USD in 2020 to an estimated 4,850.5 million USD in 2025. This trajectory underscores a resilient demand environment driven by sustained utilization in both household appliance manufacturing and construction sectors, even as the industry navigates fluctuating raw material costs and shifting regulatory expectations.
The 2026-2032 Growth Trajectory and Market Expansion
Looking ahead, the market is projected to follow a steady compound annual growth rate of 5.15 percent throughout the forecast horizon. This growth rate, while moderate, reflects the maturation of core application segments and the increasing sophistication of end-user requirements. The market size is expected to advance from approximately 5,157.81 million USD in 2026 to reach 6,893.69 million USD by 2032. This expansion is not merely a function of volume but is increasingly tied to value addition through advanced coatings, corrosion resistance warranties, and aesthetic customization.
It is important to contextualize this growth within the broader pricing environment. As of March 2026, benchmark pricing for hot-rolled coil steel in the Midwest reached 975 USD per short ton, reflecting a month-over-month increase of 2.1 percent. Furthermore, cold-rolled coil substrates, which are essential inputs for high-quality PCM production, maintain a significant premium of roughly 165 USD per short ton over hot-rolled counterparts. These input cost dynamics directly influence margin structures and pricing strategies for PCM manufacturers. Our research dissects how these cost pressures are being absorbed, passed through to downstream customers, or mitigated through process innovations and substrate substitution, such as the strategic use of aluminum or electro-galvanized steel where appropriate.
Segmentation Dynamics: Substrates, Applications, and Regional Flows
The PCM market is structurally defined by a diverse array of substrates and applications, each with distinct growth drivers and competitive intensities. The substrate landscape is dominated by galvanized steel, which continues to serve as the workhorse material for a wide range of applications due to its balance of cost, formability, and corrosion resistance. Aluminum occupies a significant secondary position, particularly in segments where weight reduction, non-magnetic properties, or specific aesthetic finishes are prioritized. Cold rolled steel also represents a critical substrate category, often selected for premium applications requiring superior surface quality and dimensional precision. The interplay between these material choices is becoming more complex as manufacturers respond to both cost volatility and performance demands.
On the application front, household appliances remain the dominant consumption pillar, absorbing the largest share of PCM sheet utilization. This segment benefits from continuous product refreshes, urbanization trends, and the replacement cycle of major white goods. Construction and infrastructure form the second major pillar, where PCM sheets are used extensively in roofing, cladding, and architectural facades. The long-term corrosion warranties often associated with these products, sometimes extending decades, highlight the critical role of coating integrity and quality assurance. Transportation and furniture represent additional application vectors, each with specific technical requirements regarding formability, surface durability, and environmental exposure.
Regionally, the market exhibits pronounced concentration patterns that reflect underlying industrial capacity and consumption centers. Asia Pacific represents the most substantial market region, reflecting the dense concentration of appliance manufacturing, construction activity, and metal processing infrastructure. Europe and North America constitute significant demand centers with mature markets that emphasize premium finishes, sustainability certifications, and regulatory compliance. Latin America and the Middle East and Africa represent emerging and developing demand pockets where industrialization, infrastructure investment, and appliance penetration rates are gradually expanding the addressable market. Our report provides a detailed, granular breakdown of these regional flows, capacity allocations, and trade dynamics, enabling readers to pinpoint where growth is most likely to materialize and where competitive saturation may be intensifying.
Concentration Dynamics and Competitive Intensity
Market concentration data reveals a landscape that is consolidated yet contested. The top three players collectively account for approximately 42.15 percent of market revenue, while the top five players extend their share to 58.6 percent. This concentration profile indicates a market where scale advantages in coating lines, raw material procurement, and distribution networks are meaningful, but where significant opportunities remain for specialized players, regional champions, and niche technology providers. The presence of a broad competitive field means that differentiation through product performance, service reliability, and supply chain resilience is essential for sustaining market position.
Competitive Landscape: Key Players and Strategic Positioning
The competitive arena for PCM metal sheets spans a global roster of integrated steel producers, specialized coil coaters, and regional manufacturers. Each participant brings a distinct strategic profile, geographic footprint, and technical capability set. Understanding how these companies position themselves is critical for benchmarking, partnership evaluation, and competitive risk assessment.
Global Integrators and Brand Leaders
BlueScope, headquartered in Australia, has established a strong reputation through its COLORBOND prepainted steel portfolio, which targets both construction and industrial applications. The company's emphasis on durability and weather-resistant performance aligns with the long lifecycle expectations of building envelope and structural applications. Similarly, NSSMC (Nippon Steel & Sumitomo Metal Corporation) from Japan operates as a major producer of coated and pre-coated steel sheets, supplying high-performance PCM-grade materials to home appliance and construction markets. Its focus on advanced corrosion resistance and aesthetic finishes positions it as a supplier of choice for applications where surface quality and longevity are paramount.
ArcelorMittal, based in Luxembourg, leverages its global scale to supply pre-painted steel through coil coating processes for building and appliance uses. Its Galvalume and related pre-paint product lines are often backed by long-term corrosion warranties, reinforcing trust in roofing, siding, and fabrication markets where performance guarantees carry substantial commercial weight. POSCO, from South Korea, produces color-coated steel sheets and PCM for both appliances and construction. Notably, the company has advanced into differentiated product development, including PosART and antiviral PCM variants, which illustrate how coating technology innovation can open new value propositions beyond conventional corrosion protection.
Regional Specialists and China-Centric Capacity
A substantial portion of global PCM capacity and production activity is centered in China, where multiple manufacturers have scaled to serve both domestic demand and export channels. Baosteel (China Baowu Steel Group) stands as a large-scale producer of PCM metal sheets for home appliances and construction, offering extensive color-coated portfolios that support high-volume downstream manufacturing. Shanghai Metal Corporation supplies PCM steel with specified thickness ranges and zinc coating parameters, tailored to electric appliance applications such as refrigerators and washing machines, and utilizes imported cold rolling equipment to maintain process quality. Everesteel, also based in China with global export reach including Australia, specializes in PCM pre-coated metal sheets and pre-painted coils for appliances and construction. The company highlights custom color matching with tight tolerances, salt spray resistance performance, and substantial annual capacity, alongside ISO 9001:2015 certification, reflecting a service-oriented approach to quality assurance.
PCM Metal Sheet Market
Other notable participants in the China-centric ecosystem include Yieh Phui (China) Technomaterial, Shandong Guanzhou, HBIS New Material, Zhuhai Speedbird PVC Film Laminated Metal Sheet Co. Ltd., and Zibo Jingtai New Material Co., Ltd. Collectively, these manufacturers contribute to a highly competitive supply environment where production scale, coating line flexibility, and cost efficiency are key differentiators. Their presence reinforces Asia's role as both a production hub and a demand center, while also shaping global pricing dynamics through export availability.
European and Asian Process Specialists
ThyssenKrupp from Germany provides coated and pre-coated steel solutions across various sectors, including appliances, leveraging European engineering standards and process expertise. In Southeast Asia, PCM Processing (Thailand) Ltd., located in Chonburi, operates as a leading Thai manufacturer of pre-painted steel sheets, including PPGI and PPGL grades, meeting international standards. The company supplies high-performance prepainted coils and sheets for household electrical appliances and offers coil center processing and embossing capabilities, which add value through post-coating customization. Dongkuk Steel and JSW Steel further broaden the competitive field, with Dongkuk focusing on pre-coated metal sheets for home appliance and industrial applications, and JSW Steel supplying pre-coated and color-coated steel sheets for appliance and building uses. JFE Steel from Japan rounds out the competitive set with high-performance pre-coated metal sheets that emphasize corrosion resistance for appliance applications.
Recent Developments and Operational Signals
Recent operational activity among key players provides useful signals about capacity utilization, quality emphasis, and market engagement. PCM Processing (Thailand) Ltd. has shared updates during 2025 reflecting ongoing facility activity and community engagement, including events and certification-related attendance, indicating sustained operational momentum and compliance focus. Everesteel has reported a zero rust claims record across more than 3,000 containers shipped in 2024, supported by ongoing lab-verified color matching services, and has released a 2025 pre-coated metal catalog covering a full range of PCM coils and film-coated metals. These developments highlight the growing importance of verifiable quality performance, consistent color matching, and catalog-driven product standardization in securing and retaining downstream contracts.
Industry Context: Compliance, Certification, and Substrates
The commercial viability of PCM products is closely tied to compliance and certification frameworks. Pre-coated metal products typically comply with ISO 9001 quality management standards and environmental directives such as RoHS. Third-party certifications from organizations including SGS, Bureau Veritas, and Intertek are commonly provided to demonstrate quality and compliance for appliance and construction applications. These certifications are not merely procedural; they function as trust mechanisms that reduce procurement risk for downstream manufacturers and construction fabricators. Additionally, environmental product declarations and lifecycle documentation are increasingly relevant, aligning PCM offerings with broader sustainability expectations in building and appliance sectors.
From a technical standpoint, PCM manufacturing generally relies on base substrates that include cold-rolled steel, electro-galvanized steel, and hot-dip galvanized steel with zinc coatings in the range of 40 to 150 grams per square meter, along with aluminum options. These substrate choices influence coating adhesion, formability, corrosion behavior, and final product cost. The availability and pricing of these substrates, combined with coating line capabilities, shape the product mix that manufacturers can offer and the value they can capture. Our research examines how substrate selection strategies are evolving in response to cost pressures, performance requirements, and customer specifications.
Why This Research Matters for 2026 Decision-Making
The strategic value of this market research lies in its ability to connect macro trends with operational implications. For sourcing and procurement teams, understanding the interplay between substrate pricing, coating technology, and regional capacity is essential for mitigating cost volatility and securing reliable supply. For product development and engineering leaders, the report provides context on coating innovations, corrosion performance benchmarks, and aesthetic customization trends that can inform material selection and design-for-manufacturing decisions. For competitive intelligence and corporate strategy functions, the analysis of market concentration, player positioning, and recent operational developments offers a framework for evaluating threats, identifying partnership opportunities, and assessing market entry or expansion feasibility.
Phase Change Material (PCM) Market
Importantly, this research is designed to support decisions that require precision. While this article outlines the broad contours of the market and the strategic themes defining 2026, the full report delivers the detailed segmentation data, regional breakdowns, application splits, and company-level assessments that executives need to quantify opportunity and risk. The complete dataset enables readers to move beyond directional insight and into scenario planning, margin modeling, and prioritization of growth initiatives.
What the Full Report Unlocks
The complete PCM Metal Sheet Market research provides an integrated view across multiple dimensions. It details the segmentation structure across regions, substrates, and applications, allowing readers to identify which segments are driving growth and which are experiencing maturation or intensification. It includes comprehensive profiles of key companies, with headquarters, product focus, and strategic context, enabling benchmarking and targeted competitive analysis. It incorporates recent developments and operational signals that reflect real-time market behavior, supporting a timely and nuanced interpretation of industry dynamics.
In addition, the report embeds industry context around raw material pricing, substrate specifications, and regulatory compliance, ensuring that strategic conclusions are grounded in the operational realities of PCM manufacturing and procurement. By combining historical data validation with a forward-looking forecast through 2032, the research offers a durable reference point for planning cycles that extend beyond the current fiscal year.
Conclusion: Positioning for Informed Action
The Pre-Coated Metal sheet market in 2026 presents a landscape shaped by steady growth, material cost dynamics, evolving substrate strategies, and a competitive field that spans global integrators and specialized regional manufacturers. Success in this environment depends on access to accurate, detailed, and actionable intelligence. This article has outlined the strategic themes and market structure that define the current period, but the depth required for confident decision-making resides in the full research publication. We invite stakeholders to access the complete report to obtain the granular market size data, segmentation breakdowns, competitive profiles, and contextual analysis needed to navigate the PCM market with clarity and precision.
For detailed analysis of this topic, please visit the official page: PCM Metal Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Micro Irrigation Market Hits $13.85B in 2025, Projected 9.5% CAGR to 2032
By PW Consulting, 2026-09-17
Unlocking Growth in the Worldwide Agriculture Micro Irrigation System Market: Strategic Intelligence for 2026 Decision-Makers
The global agriculture sector stands at a critical inflection point where water scarcity, climate volatility, and the demand for yield optimization converge to redefine operational priorities. For executives navigating the Worldwide Agriculture Micro Irrigation System Market, understanding the trajectory of this industry is no longer optional—it is a prerequisite for resilient growth. Our latest comprehensive market research report, covering the historical period from 2020 to 2025 and extending forecast insights through 2032, delivers the granular intelligence necessary to transform uncertainty into competitive advantage.
This study is designed specifically for strategic planners, investment committees, and commercial leaders who require more than surface-level statistics. By synthesizing historical performance data with forward-looking modeling, the report provides a robust framework for evaluating market entry, capacity expansion, partnership opportunities, and technology adoption. The analysis anchors on a baseline year of 2025, ensuring that all projections reflect the most current market realities while accounting for the accelerating shift toward precision water management across diverse agricultural landscapes.
Market Scale and Growth Trajectory: A Decade of Transformation
The macro picture emerging from our analysis underscores a sustained upward trajectory for micro irrigation adoption worldwide. The overall market has demonstrated consistent expansion over the past half-decade, with total revenue climbing from approximately 8,995 million USD in 2020 to 13,850 million USD in 2025. This historical momentum translates into a forecasted compound annual growth rate of 9.5 percent throughout the 2026-2032 forecast period, positioning the industry for substantial value creation well into the next decade.
By 2032, the market is projected to reach a revenue scale that reflects both incremental adoption and structural shifts in farming practices. This growth is not merely a function of population-driven food demand. Rather, it is propelled by a confluence of regulatory mandates, subsidy-driven affordability programs, technological maturation in sensor-enabled delivery systems, and an increasingly urgent corporate sustainability mandate across the agri-food value chain. Organizations that align their roadmaps with these underlying drivers will be best positioned to capture disproportionate share during the forecast window.
It is important to recognize that the 9.5 percent CAGR represents an aggregate velocity that masks significant variation across system architectures, crop categories, and regional maturity levels. The report deconstructs these variations without oversimplifying them, enabling readers to identify where growth is likely to concentrate and which structural factors will act as tailwinds or constraints in specific contexts.
Structural Segmentation and Strategic Focus Areas
Micro irrigation is not a monolithic category. The report segments the market along three primary dimensions that matter most to commercial strategy: system type, crop application, and regional deployment patterns. Each dimension reveals distinct demand drivers, pricing dynamics, and competitive intensity.
Worldwide Agriculture Micro Irrigation System Market
- System architectures divide the market between drip irrigation configurations and micro-sprinkler technologies, each addressing different agronomic requirements, water pressure constraints, and capital expenditure profiles. The report evaluates how end-users weigh initial system cost against long-term operational savings, and how evolving emitter designs and filtration standards are reshaping purchasing decisions.
- Crop-type segmentation captures the divergence in irrigation needs across orchard crops and vineyards, field crops, greenhouse operations, and other specialized applications. The analysis highlights how crop value density, root-zone sensitivity, and harvesting logistics influence the willingness to invest in precision delivery infrastructure, and where bundled solutions are gaining traction over standalone component sales.
- Regional analysis maps demand intensity across Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa, illuminating how local policy environments, water stress levels, farm structure, and distribution network maturity interact to shape market potential.
Throughout the report, we intentionally avoid presenting simplistic percentage shares or isolated dollar figures for individual segments in isolation. Instead, we contextualize each segment within the broader ecosystem, showing how cross-segment dynamics—such as the interplay between drip system adoption in high-value orchards and micro-sprinkler deployment in broader field contexts—inform total addressable market calculations and scenario-based forecasting. This approach empowers readers to build their own internal models based on a transparent analytical foundation.
Competitive Landscape: A Consolidated Arena with Differentiated Playbooks
Market concentration data indicates a moderately consolidated competitive environment, with the top three players commanding a combined share of approximately 42.5 percent and the top five firms extending their collective footprint to roughly 56.8 percent. Such concentration signals both the maturity of the industry and the strategic importance of scale, distribution reach, and technology differentiation. However, the presence of highly specialized regional players and vertically integrated manufacturers ensures that competition remains dynamic, particularly as newcomers and established firms alike pursue digital integration and localized service models.
The report profiles a curated set of leading organizations whose strategies illustrate the spectrum of approaches shaping the market:
- Netafim Ltd. (Orbia Advance Corporation) continues to leverage its pioneering heritage in drip irrigation, pairing hardware excellence with digital farming tools that enable real-time optimization of water and nutrient delivery across high-value crops such as avocados, wine grapes, corn, and sugarcane. Recent corporate moves underscore a dual focus on precision technology and large-scale partnership-driven deployment.
- Jain Irrigation Systems Ltd. operates a vertically integrated model anchored in the "More Crop Per Drop" philosophy, emphasizing water and fertilizer efficiency through ultra-low energy systems tailored to field crops, orchards, and innovative applications that expand micro irrigation into traditionally water-intensive practices.
- The Toro Company and Rain Bird Corporation both maintain strong positions in the North American market, offering comprehensive component and system portfolios that prioritize clogging reduction, emission uniformity, and water-use optimization across diverse crop production environments.
- Lindsay Corporation and Valmont Industries Inc. (Valley Irrigation) bridge large-scale center pivot and linear irrigation expertise with micro irrigation integration, enabling precision water management across expansive operations and leveraging digital platforms to optimize scheduling and resource allocation across multiple geographies.
- Rivulis Irrigation Ltd. delivers a broad micro irrigation portfolio spanning drip tapes, molded emitter lines, layflat pipes, filters, valves, and fertigation solutions, supporting field crops, orchards, greenhouses, and protected agriculture with an emphasis on manufacturing scale and regional responsiveness.
- Hunter Industries and Nelson Irrigation Corporation round out the competitive field with specialized product lines that address subsurface delivery, pressure-compensating emitters, high-uniformity micro sprinklers, and automation-enabled water management, catering to both crop production and specialized nursery or tree-vine applications.
Beyond corporate profiles, the report integrates a timeline of recent developments that illustrate how competition is shifting from hardware-only contestation toward ecosystem-level value creation. Notable examples include the introduction of AI-powered dosing product ranges for enhanced precision fertigation, collaborations aimed at deploying advanced drip irrigation at scale in high-growth agricultural markets, the launch of rotator sprinklers designed for reduced maintenance in orchard settings, facility expansions intended to shorten lead times in key regions, and patented hybrid dripline technologies that combine integral and on-line dripper configurations for labor-saving efficiency in vineyards, orchards, and greenhouses. Together, these moves signal an industry that is accelerating toward smarter, faster, and more integrated solutions.
Market Dynamics: Policy, Standards, and Input Economics as Strategic Levers
The growth narrative for micro irrigation cannot be disentangled from the policy and standards environment that frames adoption economics. Regulatory frameworks, subsidy architectures, and international standards collectively influence the cost-benefit calculus for farmers, distributors, and system integrators. The report examines several dynamics that are actively reshaping demand behavior and supply-side strategy.
Worldwide Micro Spray System Market
- Standardization efforts, such as international guidelines for the implementation of pressurized drip irrigation systems, provide a reference architecture that supports consistent performance expectations and reinforces the water-saving potential of properly designed micro irrigation configurations for both small-scale and large-scale operations.
- National datasets from major agricultural economies reveal a pronounced structural shift toward pressurized irrigation systems, including micro and drip technologies, across substantial portions of irrigated cropland in Western agricultural regions, reflecting a long-term preference for efficiency gains that compound over time.
- Subsidy programs continue to play a decisive role in accelerating adoption among small and marginal producers. In key markets, government schemes have extended substantial coverage across millions of hectares through 2024, with differentiated subsidy rates that make micro irrigation systems more accessible while maintaining quality benchmarks through component certification requirements.
- Large-scale public investment announcements in select regions have signaled intent to modernize irrigation infrastructure and reduce agricultural water consumption through advanced technologies, creating both near-term procurement opportunities and longer-term demand stability for system suppliers.
- Input economics remain a critical factor, as micro irrigation systems rely heavily on polymer-based tubing and emitters whose costs are sensitive to raw material markets. Subsidy eligibility frameworks in certain programs tie financial support to the use of certified components, meaning that supply chain compliance and material sourcing strategies carry direct commercial implications.
By treating these dynamics as interconnected rather than isolated, the report helps decision-makers anticipate how changes in subsidy policy, standards adoption, and raw material pricing may alter competitive conditions, margin structures, and time-to-market expectations across different geographies and customer segments.
What the Report Delivers: Operational Intelligence for Concrete Decisions
This market research is built to support action, not just observation. Readers will find a structured body of content designed to feed directly into strategic planning processes, investment appraisals, and commercial execution plans. Key contents include:
- A rigorous historical reconstruction of market performance that establishes baseline credibility and identifies inflection points across the 2020-2025 period.
- A forecast model extending through 2032 that integrates growth drivers, constraints, and scenario considerations, enabling internal sensitivity testing rather than reliance on a single point estimate.
- Segmentation analysis that clarifies where system types, crop categories, and regional opportunities intersect with corporate capabilities and distribution strengths.
- Competitive profiling that maps strategic positioning, product portfolio depth, technology direction, and recent corporate activities for leading market participants.
- Market dynamics coverage that connects policy, standards, subsidy design, and input economics to adoption behavior and supply-side implications.
- Practical guidance for interpreting concentration metrics, evaluating partnership and M&A opportunities, and assessing where differentiation is most defensible in a maturing market.
Throughout, the report maintains a disciplined standard: it provides enough analytical depth to establish trust and credibility, while reserving the most granular segment-level data for the full publication. This design reflects a deliberate philosophy. High-level market direction and structural logic are essential for initial strategic alignment, but precise figures, sub-segment splits, and detailed regional breakdowns are most valuable when integrated into proprietary planning models. By accessing the complete report, decision-makers gain the full quantitative foundation required to benchmark internal assumptions, calibrate revenue targets, and prioritize resource allocation with confidence.
Why This Research Matters for 2026 Strategy
As organizations formulate their 2026 agendas, the Worldwide Agriculture Micro Irrigation System Market presents both opportunity and complexity. The convergence of sustained demand growth, increasing market concentration, accelerating technology integration, and evolving policy frameworks means that strategy cannot be built on anecdotal evidence or lagging indicators alone. Companies need a current, methodologically consistent view of where value is being created, how competitive pressure is shifting, and which structural trends will endure beyond short-term cycles.
This report is intended to serve as that reference point. It equips leadership teams with the context to evaluate market entry timing, assess the strategic fit of potential partnerships or acquisitions, interpret competitor moves within a broader trajectory, and align commercial execution with the demand realities of farmers, absentee landowners, cooperative bodies, and institutional agri-operators. Whether the objective is to expand geographic reach, deepen product differentiation, or improve go-to-market efficiency, the analysis provides a calibrated foundation for informed decision-making.
For executives who require the complete dataset, sub-segment breakdowns, regional modeling detail, and full competitive intelligence to finalize their 2026 plans, the full report offers the comprehensive intelligence necessary to act decisively. The macro trajectory is clear. The strategic value lies in translating that trajectory into precise, company-specific action. Our research is designed to make that translation possible.
For detailed analysis of this topic, please visit the official page: Worldwide Agriculture Micro Irrigation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Military Protective Gear Market to Hit $22.93B by 2032, 4.5% CAGR
By PW Consulting, 2026-09-17
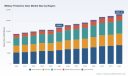
Navigating the Future of Defense Protection: Strategic Insights from the Worldwide Military Protective Gear Market 2026–2032
The global defense landscape is undergoing a profound transformation. As military forces worldwide recalibrate their operational doctrines, the demand for advanced protective gear has evolved from a commodity consideration to a critical strategic imperative. At PW Consulting, we recognize that informed decision-making in this sector requires more than surface-level observations. It demands a granular understanding of market trajectories, competitive dynamics, material science advancements, and the regulatory currents shaping procurement behaviors.
Our newly published Worldwide Military Protective Gear Market research report is designed precisely for this purpose. Serving as a comprehensive strategic compass, this study equips defense contractors, material suppliers, investment firms, and government procurement analysts with the intelligence needed to navigate the complex terrain of military personal protection through 2032. This article serves as a strategic preview, highlighting the analytical depth, actionable frameworks, and forward-looking perspectives embedded within the full report, while demonstrating why this intelligence is indispensable for enterprise strategy in 2026 and beyond.
The Macro Landscape: Resilient Growth Anchored in Strategic Shifts
The worldwide military protective gear market has demonstrated remarkable resilience and steady expansion over the past half-decade. Drawing on historical performance data from 2020 through 2025, the sector has consistently grown, culminating in a base-year valuation of approximately 16,850.5 million USD in 2025. This progression reflects not only post-pandemic procurement normalization but also the accelerating modernization of armed forces, heightened geopolitical tensions, and the ongoing integration of advanced materials into personal protection systems.
Looking ahead, our forecast models project a clear upward trajectory. The market is anticipated to expand from roughly 17,877.5 million USD in 2026 to over 22,931.2 million USD by 2032, translating to a compound annual growth rate of 4.5 percent. This growth rate is neither speculative nor overstated; it is derived from rigorous bottom-up analysis that accounts for defense budgeting cycles, procurement lead times, inventory replenishment patterns, and the steady adoption of next-generation protective technologies. For strategic planners, this CAGR represents a sustainable expansion environment—one where long-term capacity planning, R&D investment, and supply chain optimization can yield compounding returns.
It is worth noting that this growth is not uniformly distributed across all market dimensions. The interplay between regional defense spending priorities, product-category evolution, and application-specific procurement drives creates distinct value pools. Understanding where capital is flowing, which procurement channels are gaining prominence, and how material preferences are shifting requires a detailed segmentation analysis that the full report provides in depth.
What the Report Delivers: A Blueprint for Actionable Intelligence
Market research at its best does not merely describe what has happened; it equips leaders to anticipate what will happen and act accordingly. Our Worldwide Military Protective Gear Market report is structured around this principle. It combines macroeconomic forecasting with granular operational insights, delivering a multi-layered analytical framework that supports everything from M&A targeting to product roadmap development.
At its core, the study offers a comprehensive segmentation architecture that dissects the market by region, product type, and application. Each segment is evaluated through the lens of demand drivers, procurement maturity, technological adoption curves, and competitive intensity. This allows readers to identify high-growth niches, assess market saturation risks, and benchmark their positioning against industry norms. Rather than presenting isolated statistics, the report weaves these dimensions into a cohesive narrative that explains how structural factors interact to shape market outcomes.
Worldwide Military Protective Eyewear Market
Beyond segmentation, the report provides an extensive competitive landscape analysis. Thirteen leading companies are profiled, with detailed assessments of their headquarters, core competencies, technological focus areas, and strategic positioning. These profiles go beyond corporate bios; they examine how each player leverages material science, manufacturing scale, government relationships, and innovation pipelines to capture share. Special attention is given to firms that have recently demonstrated momentum through contract extensions, major procurement awards, or strategic acquisitions, offering readers a real-time pulse on industry consolidation and capability expansion.
The study also incorporates a forward-looking analysis of market dynamics. Here, we explore the forces that will dictate competitive advantage in the coming years: raw material pricing pressures, regulatory compliance requirements, geopolitical procurement shifts, and the growing emphasis on multi-threat, lightweight protective systems. By contextualizing these dynamics within the broader market trajectory, the report enables readers to stress-test their strategies against plausible future scenarios.
Additionally, the report addresses practical operational considerations that often fall outside traditional market sizing exercises. Topics such as export control frameworks, international ballistic testing standards, and regional procurement preferences are examined for their implications on market access, supply chain design, and partnership strategies. For global players, these insights are critical to avoiding compliance pitfalls and aligning product portfolios with the expectations of key defense customers.
Competitive Architecture: Leaders, Innovators, and the Battle for Capability
The military protective gear sector is characterized by a concentrated yet dynamic competitive landscape. Our analysis indicates a market structure where a handful of dominant players command significant share, yet specialized innovators and regional manufacturers continue to carve out defensible positions through technological differentiation and niche procurement relationships.
Worldwide Military Protective Gear Market
Prominent incumbents such as 3M Company, BAE Systems, and Gentex Corporation anchor the upper tier of the market. 3M leverages its broad materials portfolio to deliver lightweight composites and multi-threat personal protection systems. BAE Systems focuses on integrated soldier systems, emphasizing modular armor architectures and advanced material integration for global military deployments. Gentex has carved a distinct niche in combat helmet innovation, particularly through its Advanced Combat Helmet programs and communication-integrated head protection platforms, recently extending its production support under a multi-year contract framework with the Defense Logistics Agency.
In the body armor and tactical vest segment, Point Blank Enterprises maintains a strong footprint through its focus on ballistic plates, shields, and protective vests tailored to U.S. military and Department of Defense requirements. DuPont and Honeywell International operate as critical upstream enablers, with DuPont's aramid fiber technologies and Honeywell's Spectra Shield composites serving as foundational materials for high-performance ballistic solutions across multiple end-users. Avon Protection rounds out the leadership cohort with its expertise in respiratory and CBRN defense systems, reflecting the market's growing emphasis on integrated, multi-hazard protection.
Beyond these established players, a vibrant ecosystem of specialized manufacturers drives innovation at the tactical level. ArmorSource LLC and Revision Military focus on lightweight helmet and eye-protection systems designed for dismounted operations, while Safariland and MKU Limited maintain strong positions in tactical carrier systems and export-oriented ballistic protection, respectively. In the Asia-Pacific manufacturing corridor, Ningbo Chowey Police Equipment Co., Ltd. has expanded its footprint in bulletproof vests, helmets, and tactical accessories, aligning with the broader shift toward diversified, internationally compliant supply chains.
Recent industry developments underscore the intensity of this competitive environment. In late 2025, the U.S. Army awarded substantial delivery orders for lightweight small arms protective insert plates, signaling sustained demand for enhanced ballistic performance without compromising weight thresholds. Simultaneously, strategic acquisitions such as Double Tap Industries LLC's absorption of Caliber Armor illustrate how market participants are consolidating capabilities to broaden product lines and strengthen their positioning across military and law enforcement segments. These moves are not isolated; they reflect a broader trend in which companies are actively reshaping their portfolios to capture emerging requirements in modularity, weight reduction, and multi-spectrum protection.
Market Dynamics: The Forces Reshaping Procurement and Innovation
Understanding the competitive map is only half the equation. The real strategic value lies in grasping the underlying dynamics that will determine which companies thrive and which struggle to maintain relevance. Several interconnected forces are currently redefining the military protective gear market.
Raw material economics remain a persistent pressure point. Advanced ballistic materials, particularly aramid fibers and UHMWPE-based composites, command premium pricing due to high manufacturing complexity and ongoing R&D investment aimed at achieving lightweight, multi-hit performance. For OEMs and system integrators, this translates into a constant balancing act between performance specifications, cost structures, and procurement budgets. Companies that can secure reliable material supply, optimize composite architectures, or introduce alternative high-performance fibers will hold a distinct advantage in margin management and contract competitiveness.
Regulatory and compliance environments further complicate market access. Stringent international ballistic testing standards require continuous third-party validation, and certifications must be maintained across multiple export markets to ensure interoperability and buyer confidence. In parallel, export control frameworks such as the U.S. International Traffic in Arms Regulations impose restrictions on certain ballistic technologies and materials, requiring careful licensing strategies for companies seeking to expand their international footprint. Navigating these requirements is not merely a legal exercise; it is a strategic capability that determines which markets are accessible and how quickly a company can scale into new regions.
Geopolitical recalibration is perhaps the most transformative dynamic of the current cycle. Rising NATO defense spending commitments, including the push toward 2 percent of GDP and a growing preference for European-sourced procurement by 2030, are driving demand for localized manufacturing and regional supply chain resilience. This shift is prompting both incumbent suppliers and new entrants to evaluate production footprints, partnership structures, and technology transfer arrangements. For companies with global ambitions, the ability to align with regional procurement preferences while maintaining technical and quality standards will be a defining factor in capturing government and allied contracts.
Together, these dynamics create a market environment that rewards agility, technical depth, and strategic foresight. The companies that succeed will be those that treat compliance, material innovation, and regional alignment not as operational afterthoughts but as core components of their growth strategy.
Why This Research Is Critical for 2026 Decision-Making
As organizations enter 2026, the decisions made today will shape competitive positioning for the remainder of the decade. Whether you are evaluating capacity expansion, assessing M&A targets, refining a product roadmap, or advising government clients on procurement optimization, the margin for guesswork is narrowing. Market intelligence must be precise, forward-looking, and directly applicable to operational strategy.
Our Worldwide Military Protective Gear Market report is built for exactly this moment. It provides the analytical scaffolding needed to move from high-level awareness to concrete action. Readers will gain clarity on which product categories are experiencing the strongest demand momentum, how regional procurement patterns are evolving, and where the competitive center of gravity is shifting. The report's company profiles, market dynamics analysis, and segmentation frameworks are designed to inform investment thesis development, partnership targeting, and risk assessment in a sector where technological advantage and procurement access are tightly intertwined.
Importantly, the full report contains detailed regional and application-level data, granular segmentation values, and comprehensive competitive metrics that are essential for precise strategic planning. While this overview highlights the structure and strategic relevance of the study, the complete dataset and in-depth analyses are available through the full report. We encourage defense industry executives, investment professionals, and policy-adjacent analysts to review the complete publication to ensure their 2026 strategies are grounded in the most current and comprehensive market intelligence available.
Conclusion: Strategic Clarity in a Rapidly Evolving Sector
The worldwide military protective gear market is entering a phase of sustained, structurally supported growth. Driven by modernization programs, evolving threat environments, and the relentless pursuit of lighter, more capable protection systems, the sector presents both opportunity and complexity. Success in this environment requires more than broad market awareness; it demands a detailed understanding of segmentation dynamics, competitive positioning, material and regulatory constraints, and regional procurement shifts.
PW Consulting's Worldwide Military Protective Gear Market research report delivers that understanding. By combining rigorous forecasting with practical, operationally relevant analysis, the study equips leaders to make confident, evidence-based decisions as they navigate the years ahead. For those committed to staying ahead of the curve in defense protection, the insights within this report are not just valuable—they are essential.
For detailed analysis of this topic, please visit the official page: Worldwide Military Protective Gear Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Face & Voice Biometric Market Hits $7,481M in 2025, 14% CAGR to $18.7B by 2032
By PW Consulting, 2026-09-17
Beyond the Password: Strategic Intelligence for the Face Voice Biometric Market 2026-2032
The enterprise authentication landscape is undergoing a structural shift. Passwords and tokens are no longer sufficient anchors for digital identity. As financial services, government agencies, and consumer technology companies confront rising synthetic fraud and remote access demands, face and voice biometrics have emerged as the primary modalities for multi-factor verification. Yet the market is not a monolith. It is a complex ecosystem shaped by hardware latency constraints, regulatory classification, and the pace of liveness detection certification. For executives planning capital allocation and product roadmaps in 2026, understanding where the market stands and where it is heading requires more than headline figures. It demands a granular view of segment growth, competitive positioning, and the compliance variables that will define deployment viability.
This article previews the strategic intelligence contained in our newly released Worldwide Face Voice Biometric Market research report. The following analysis maps the macro trajectory, dissects the competitive field, and outlines the operational frameworks buyers and vendors must navigate. The full report provides the segmented data, regional breakdowns, and company-level benchmarking required to convert these trends into executable decisions.
Worldwide Face Voice Biometric Market
Market Trajectory and the 2026 Decision Window
The global face voice biometric market has moved from early adoption to scaled deployment. Revenue expanded from approximately USD 3.4 billion in 2020 to an estimated USD 7.5 billion in 2025, reflecting a compound annual growth rate of 14.0 percent. The forecast horizon through 2032 indicates continued acceleration, with market size projected to reach USD 18.7 billion by the end of the period. The 2026 outlook places the market at roughly USD 8.4 billion, a threshold that signals maturity in several core applications while leaving substantial room for expansion in emerging verticals.
These aggregate figures tell a directional story, but they do not reveal the operational realities that determine win rates and deployment timelines. Decision-makers need to understand how growth distributes across solution types, which applications are pulling ahead, and where regional dynamics create asymmetric opportunities. The report isolates these layers without oversimplifying them, enabling buyers to benchmark their procurement timing against adoption curves and allowing vendors to identify whitespace before competitors lock in channel partnerships.
For enterprise strategists, the 2026-2032 window is critical. Budget cycles are being set now against a backdrop of tightening identity assurance requirements and increasing fraud sophistication. Organizations that delay biometric integration risk falling behind on customer experience expectations and compliance posture. Conversely, organizations that move without a clear segmentation strategy may overinvest in hardware-dependent deployments or misalign with the regulatory frameworks that govern biometric data processing in their target markets. The report is designed to reduce that ambiguity.
Report Scope: What the Analysis Delivers
The Worldwide Face Voice Biometric Market research is structured for practical decision-making rather than abstract observation. It combines historical reconstruction with forward-looking forecasting and integrates company-level intelligence to give stakeholders a complete operational view. Key components include:
- Revenue mapping across the 2020-2025 historical period and a detailed 2026-2032 forecast, with growth drivers and headwinds explicitly modeled rather than implied.
- Segmentation analysis by solution type, application, and region, showing where value is concentrating and how share is shifting among software, hardware, and services delivery models.
- Application-level insights across BFSI, government and defense, consumer electronics, healthcare, and retail and e-commerce, with attention to adoption drivers, integration complexity, and vendor fit.
- Company profiling for leading participants, including headquarters, product architecture, recent launches, partnerships, certifications, and pilot deployments that indicate strategic direction.
- Market concentration metrics that clarify the balance between incumbent scale and emerging challenger activity, helping buyers assess vendor durability and pricing leverage.
- Regulatory and standardization context, including high-risk AI classification regimes, presentation attack detection protocols, and biometric data processing requirements that shape deployment feasibility.
- Technology enablers and bottlenecks, with focus on edge processing requirements, latency thresholds, and liveness detection maturity that determine real-world performance.
The report avoids the common trap of presenting segmentation as a static snapshot. Instead, it treats splits as dynamic indicators of where investment is flowing, where friction persists, and where differentiation is still possible. Readers looking for exact regional shares, application-level revenue figures, and solution-type breakdowns will find them in the full dataset, where the numbers are presented with the caveats, assumptions, and segmentation logic required for sound interpretation.
Competitive Landscape: Eight Players Shaping the Next Cycle
The face voice biometric field is contested by a mix of established multinational suppliers and specialized identity technology firms. The report profiles eight companies whose recent activity signals where the market is heading in 2026 and beyond.
NEC Corporation continues to extend its NeoFace platform into multi-modal surveillance and enterprise security, most recently with an enhanced NeoFace Watch release that integrates voice biometrics for real-time authentication. Aware Inc. has pushed its Knomi face and voice SDK deeper into mobile authentication ecosystems, including a notable integration path into Android frameworks for government and financial use cases. ID R&D, operating under its Neurotechnology lineage, has reinforced its liveness detection positioning with IDVoice and IDLive Face, achieving iBeta Level 2 PAD certification that strengthens its suitability for call centers and access control environments.
Daon Inc. has been advancing its IdentityX platform as a combined face, voice, and behavioral biometrics solution, with a recent European bank pilot demonstrating KYC verification in a mobile app setting. Voice Biometrics Group focuses on voice-centric authentication with facial integration for contact center fraud prevention and remote identity verification. Thales Group supplies multi-modal biometric solutions for border control and digital identity through its SafeNet platform, reinforcing the public-sector and travel-adjacent opportunity set. HID Global brings face and voice biometrics into mobile authenticators for physical and logical access, aligning biometric identity with enterprise access management. Verint Systems anchors voice biometrics and facial recognition in customer authentication and workforce management, particularly across contact center operations.
The strategic takeaway for buyers is that no single supplier dominates every dimension. Some vendors lead in multi-modal surveillance and enterprise security, others in SDK-based mobile authentication, and others in certified liveness detection or access control integration. For vendors, the report highlights where differentiation is being established through certifications, partnerships, and pilot deployments rather than product announcements alone. The competitive landscape section goes beyond descriptive profiles to map positioning, recent moves, and the implications for procurement strategy, partnership formation, and go-to-market timing.
Biometric Scan Software Market
Market Dynamics: Regulation, Standards, and Technology Constraints
Growth in face voice biometrics is not simply a function of demand. It is increasingly governed by the regulatory and technical environment in which deployments operate. The EU AI Act classifies facial recognition and voice biometrics as high-risk AI systems, requiring conformity assessments under Title III. This classification affects product roadmaps, vendor eligibility, and the cost of market entry for providers targeting European customers. At the same time, GDPR Article 9 continues to restrict biometric data processing, requiring explicit consent or a clear legal basis for face-voice authentication. Organizations operating across jurisdictions must therefore design identity flows that can satisfy both risk classification and data protection requirements without degrading user experience.
Standardization is another force shaping procurement and product design. ISO/IEC 30107-3 specifies presentation attack detection protocols for face and voice biometrics, creating a shared reference point for liveness detection claims. NIST’s ongoing evaluations, including voice integration benchmarks under IR 8038, further tighten the performance expectations placed on algorithm providers. These frameworks matter because they influence not only compliance but also buyer confidence. Vendors that can demonstrate alignment with recognized PAD protocols and independent benchmarking are better positioned to win in regulated environments. The report tracks these standards and evaluations as living variables rather than static references, showing how they interact with certification milestones and deployment eligibility.
Technology constraints also define the pace of adoption. Real-time face-voice matching increasingly depends on edge AI processors with neural processing units capable of sustaining sub-100ms latency in mobile and embedded settings. This hardware bottleneck affects solution design, particularly for software-centric deployments that must rely on device-level processing to meet response-time expectations. The report examines how hardware-dependent and software-centric models diverge in cost structure, deployment complexity, and suitability across applications, helping buyers anticipate integration requirements and avoid mismatched architecture choices.
Strategic Implications for 2026 Decision-Making
For enterprise leaders, the face voice biometric market in 2026 presents both opportunity and execution risk. The macroeconomic trajectory is favorable, but the value capture depends on strategic clarity. The report translates market data into actionable guidance across several dimensions:
- Procurement timing: Understanding which applications are moving from pilot to production helps organizations sequence investments rather than treat biometric authentication as a single isolated project.
- Vendor selection: Profiles and recent developments reveal where suppliers are strengthening liveness detection, expanding mobile integration, or demonstrating regulatory readiness, allowing buyers to match capabilities to their own risk and compliance profile.
- Segment alignment: Recognizing how software, hardware, and services revenue splits reflect differing deployment models helps enterprises choose the architecture that best fits their existing infrastructure and latency requirements.
- Regional planning: Regional dynamics influence not only demand intensity but also the regulatory and certification burden associated with deployment, making geographic strategy a core part of product and procurement planning.
- Competitive positioning: For vendors and investors, concentration data and company-level movement provide a basis for assessing where market share is being contested and where partnerships or acquisitions may reshape the field.
The full report extends these implications with the segmented data, regional depth, and benchmarking detail needed to turn strategic direction into operational plans. It is designed for teams that must justify investment, select vendors, build roadmaps, or assess competitive exposure with evidence rather than extrapolation.
Conclusion: Converting Intelligence into Execution
The Worldwide Face Voice Biometric Market is entering a phase where scale and scrutiny grow together. Demand is expanding across financial services, government, consumer technology, healthcare, and retail, but deployment success increasingly depends on certification, regulatory alignment, latency performance, and vendor fit. Aggregate market growth signals opportunity; the segmented reality determines whether organizations can capture it efficiently.
Our newly released report provides the depth required to navigate that reality. It combines historical and forecast analysis, segmentation logic, company profiling, and dynamic market context into a single decision-support framework. Executives who need precise regional shares, solution-type revenue breakdowns, application-level figures, and concentration metrics will find them in the complete dataset, where the numbers are presented with the analytical structure necessary for confident action.
For organizations planning 2026 identity strategy, the gap between headline growth and executable insight is where competitive advantage is decided. The full report is available for teams ready to move from trend awareness to evidence-based deployment, vendor selection, and market positioning.
For detailed analysis of this topic, please visit the official page: Worldwide Face Voice Biometric Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com